A nice setup to try a 2.4-to-1 play from the short side in QQQ
One of my favorite cities on my Route 66 trip was Santa Fe.
I particularly enjoyed Meow Wolf, a strange but awesome interactive art experience.
A nice setup to try a 2.4-to-1 play from the short side in QQQ
One of my favorite cities on my Route 66 trip was Santa Fe.
I particularly enjoyed Meow Wolf, a strange but awesome interactive art experience.
Short QQQ at 754
Stop loss 772.55
Take profit 708.55
Short 4.95/5.05 USDBRL strangle
and buy 4.80/5.20 to protect.
Max gain is what you receive: ~1.65% off 4.98 spot.
Max loss is 1.35%.
Yesterday I wrote a bit that follows up on prior work I have done showing that bad breadth near the ATH is not empirically bearish. Coincidentally, Jonathan Krinsky, the esteemed technician / Managing Director at BTIG, has been writing with a lean in the opposite direction recently, highlighting his concerns about bad breadth. His work on index vs. breadth divergence has particularly focused on some market structure similarities to the 2000 bubble pop, particularly within the semiconductor universe. His 2000 vs. now SOX analog, for example, has held remarkably well through recent ups and downs.
Anyway, if you don’t subscribe to his stuff, you definitely should. He emailed me yesterday to kind of / sort of rebut what I had said about breadth—his point was that bad breadth at the ATH in isolation is not necessarily bearish, as I have shown, but bad breadth near the ATH with treasury vol near 52-week highs and HY widening should be more concerning.
I am always nervous about overparameterizing backtests and event studies in search of bearish patterns because this is an important way permabears have stayed wrong throughout the S&P 500 rally from 1000 to 8000, 2009 to 2026. If you look hard enough, you can always find a combination of variables that is in force today and was bearish in the past. This is especially true now that Claude has turned backtesting into a trivial task for anyone with experience. But all that said—treasury vol at a 1-year high and high-yield widening are logical conditions that don’t feel like cherry picking.
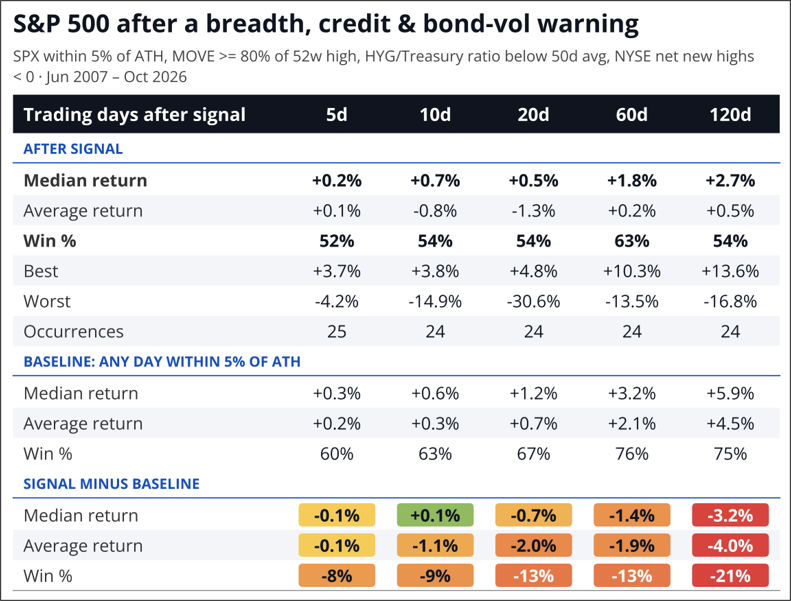
So, I ran it. Keep in mind that it is generally rare to find any backtest of initial conditions that shows bearish forward returns in an asset that has gone up eightfold over the period tested. The trend often dominates the output. So if you find something bearish without cherry picking or overtuning your parameters, it’s definitely interesting. So combining my conditions with Jonathan’s, I tested:
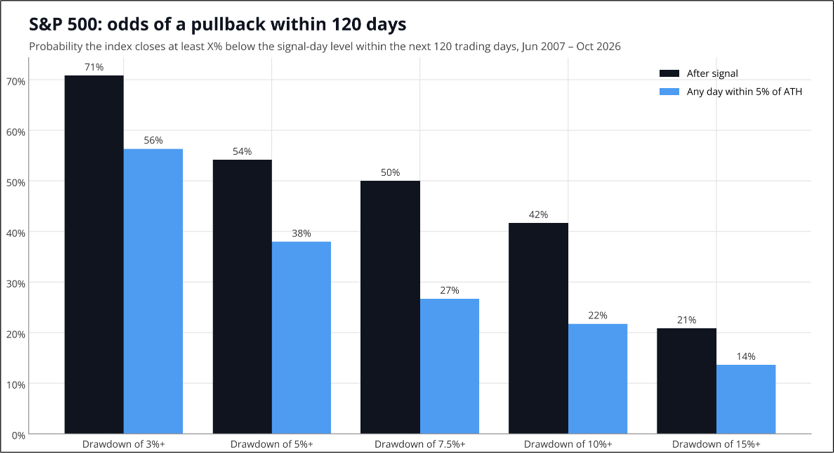
The results are convincingly bearish relative to baseline, but not outright bearish. The signal tends to precede six months of unusually weak returns.
What the results show:
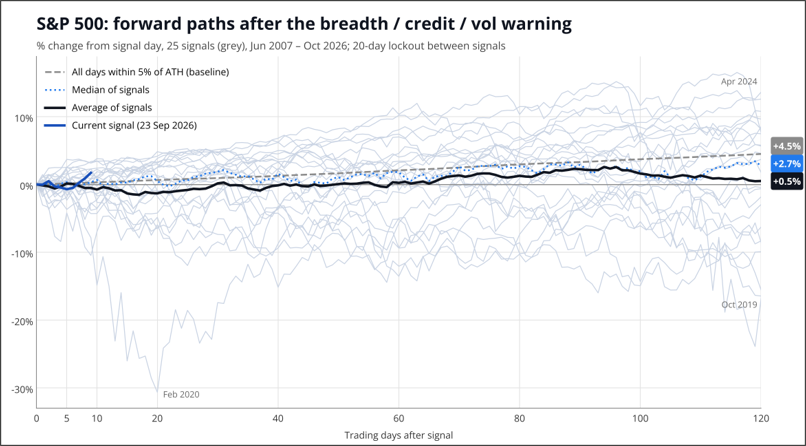
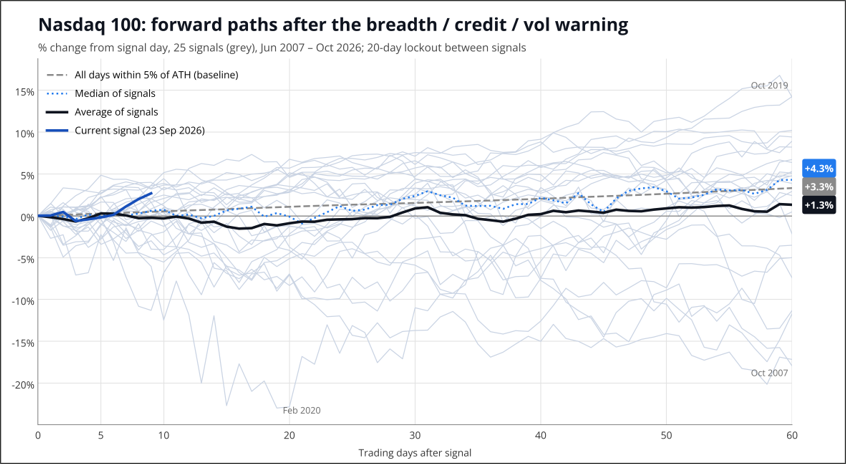
NASDAQ looks similar, naturally…
S&P correction odds after and without signal.
And one last chart to show all the results, one by one.
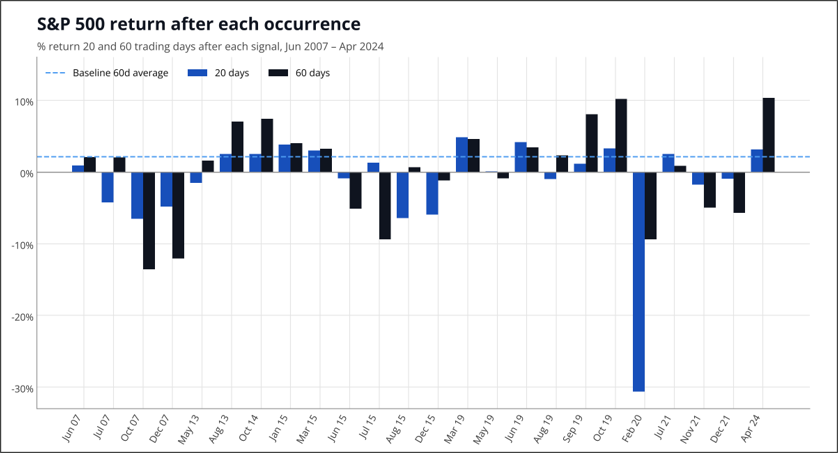
Conveniently, this analysis comes after a rather epic rally in QQQ, and at a time when bitcoin, silver, and gold all finally trade weak. The strength in crypto in the past week or two has made it particularly tough for me to have a bearish equity view because it indicated to me that animal spirits were still alive. Now, with the break to the ATH in stonks, tightening financial conditions, a zippy move in bonds today, this backtest, weakness in crypto, and a stellar entry point… I think this is a great time to take a shot selling QQQ. I am adding it to the sidebar.
Short at 754 with a stop 2 ATRs away at 772.55. Take profit 708.55. Risk 19 to make 45.
Not investment advice. Simply sharing my ideas. Trade your own view. Regular readers know how I roll when it comes to shorting equity indexes. I am not a permabear. I will sell here and if I get stopped out, I will move on to the next idea. I have no emotional attachment. I just think this is a great place to take a shot. Thanks to Jonathan Krinsky for taking the time to email. His points helped greatly.
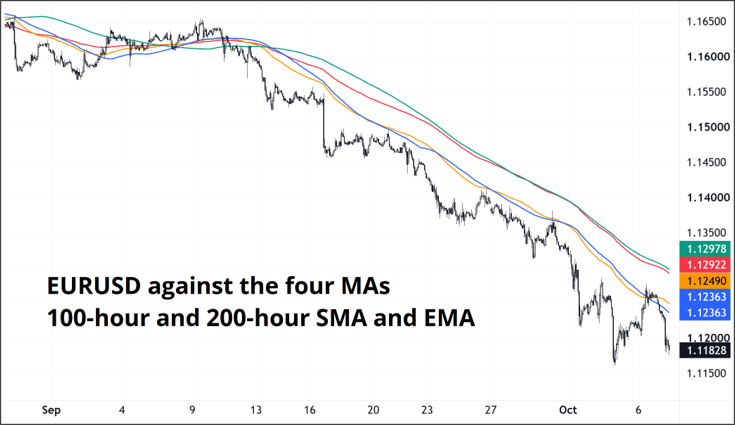
EURUSD did the perfect test of 1.1270/20 and is trading exactly as you’d hope would if you are short. GBPUSD joining the party now too. The old daily levels which I have been discussing in here for ages were 1.1270/1.1320 and the high yesterday was 1.1277 so that’s a perfect weak retest and fail. Look at the price vs. the moving averages. That’s a trend! With positioning quite long USD, I still think we could see more choppy moves in EURUSD and EURCHF with a bias lower. French spreads haven’t widened enough yet today to justify new lows in the euro.
Have a strange and artistic day.
One of my favorite cities on my Route 66 trip was Santa Fe.
I particularly enjoyed Meow Wolf, a strange but awesome interactive art experience.