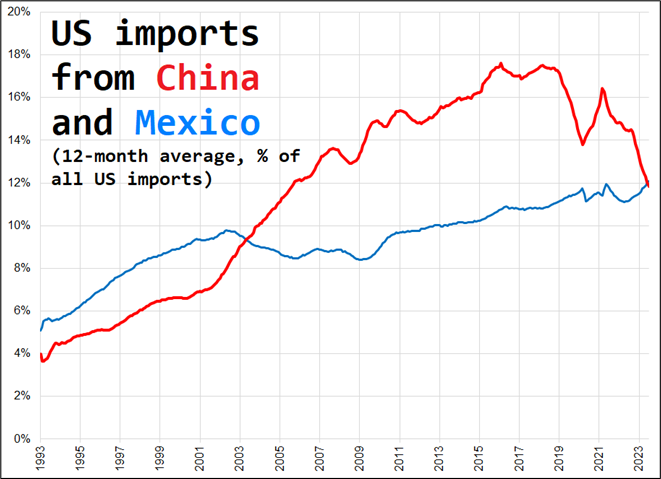
Some CPI analysis and a nice chart on Mexico that you might have already seen on Bloomberg or from BofA.
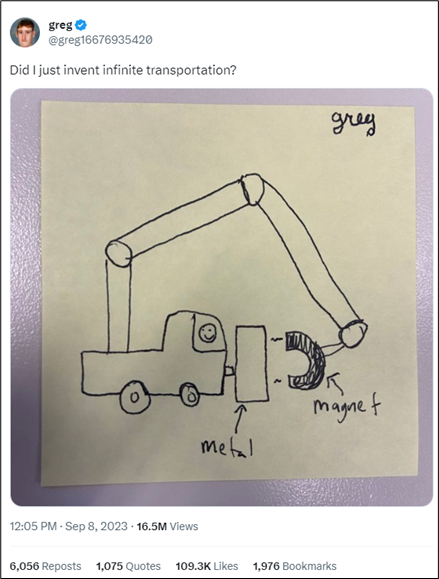
The comments and Greg’s responses to the comments on this post are comedy gold
https://twitter.com/greg16676935420/status/1700178590761894033

Some CPI analysis and a nice chart on Mexico that you might have already seen on Bloomberg or from BofA.
The comments and Greg’s responses to the comments on this post are comedy gold
https://twitter.com/greg16676935420/status/1700178590761894033
Buy 1-month 17.00 USDMXN put
when spot gets to 17.4980
September 12, 2023
USDMXN has been the great story of 2023 and it’s kind of cool when the basic fundamental story aligns with the market move. Here’s an epic chart:
While Banxico triggered a decent reversal off the 17.00 level, and I’m generally opposed to fighting central bank currency messaging, my bet is that USDMXN retests sub-17 and a multi-month cat and mouse game will develop as the market tries to determine whether or not the Banxico actually cares that much or if they were just sending a warning flare like the Riksbank but have no strong desire to battle market and economic forces.
The Mexican budget yesterday stopped the uptrend and now we can go back to the regularly-scheduled down trend. If it wasn’t for CPI, I would buy a 1-month 17.00 USDMXN put and take profit if we get to 16.85. That is a trade you can put on after a strong CPI as you might get a nicer entry point closer to 17.50. I am putting that in the sidebar in case I don’t get am/FX out before tomorrow’s CPI release.
I outlined yesterday that I think the skew of the CPI distribution is to the high side, and I will add one more reason today (inspired partially by an email from CC). The Prices Paid component of ISM was up 5.8 points this month.
That series has a decent relationship to CPI, as one might expect. Here’s the raw data, compared below.
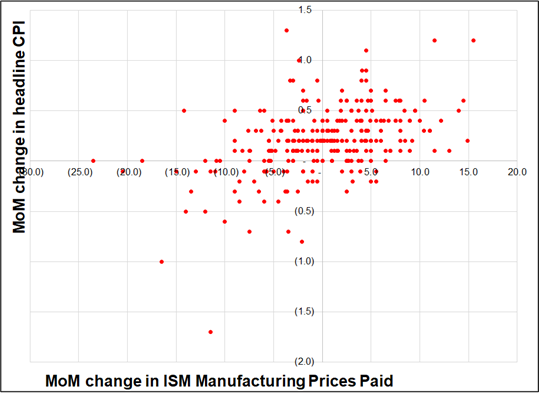
The real question, though, is whether jumps in ISM Prices Paid predict misses in CPI. The answer is yes. This suggests that economists mildly undervalue the information in the ISM Prices Paid series. Using the simplest possible analysis back to the year 2000, going with the direction of Prices Paid has been correct 97 times and wrong 79 times. There were 286 releases in total, and 100 of them were as expected. So this is another small lean in the direction of a stronger CPI tomorrow. I would not be spending money on options, though, because “as expected” is becoming more common.
CPI was kind of impossible to forecast there for a while, but the job is getting easier. Here is the complete record with “as expected” in bad student that highlights way too much in university yellow.
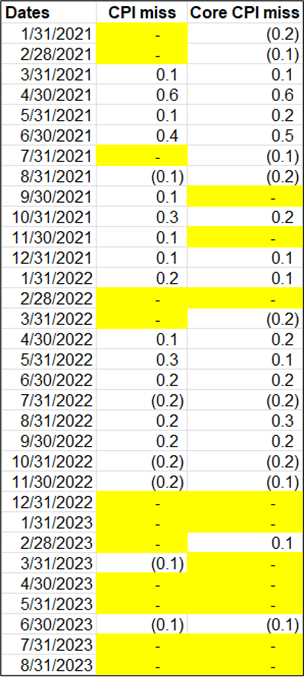
So the base case is a boring, as expected number and the distribution is skewed to the right (higher by 0.1 on both measures) in my opinion. Do with that what you will!
As has been the case just about every time the BOJ has done something on rates (including the famed rate cut below zero in 2016), the half-life of the USDJPY move was exactly one day. Now, we go back to watching US 10-year yields with an auction, US CPI, and Retail Sales all coming bam bam bam. Should be an interesting 48 hours.
The New York Jets story last night, with all its emotional ups and downs, reminded me of one my favorite things ever written. A Chinese fable.
There was once a farmer in ancient China who owned a horse. “You are so lucky!” his neighbors told him, “To have a horse to pull the cart for you.”
“Maybe,” the farmer replied.
One day the farmer forgot to latch the gate and his horse bolted. “Oh no! This is terrible news!” his neighbors cried. “Such terrible misfortune!”
“Maybe,” the farmer replied.
A few days later the horse returned, bringing with it six wild horses. “How fantastic! You are so lucky,” his neighbors told him. “Now you are rich!”
“Maybe,” the farmer replied.
The next week, the farmer’s son was breaking in one of the wild horses when he fell off and broke his leg. “Oh no!” the neighbors cried, “such bad luck!”
“Maybe,” the farmer replied.
The next day soldiers came and took away all the young men to fight in the war. The farmer’s son was left behind due to his injury. “You are so lucky!” his neighbors cried.
“Maybe,” the farmer replied.
Have an infinitely powerful day.
The Spectra FX Positioning and Momentum Report
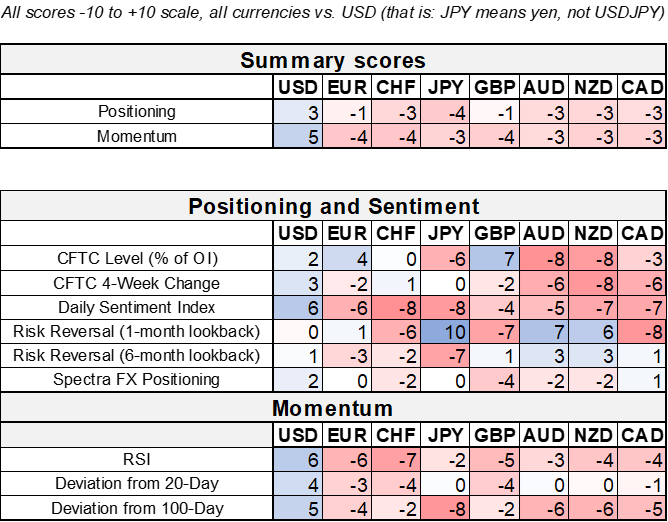
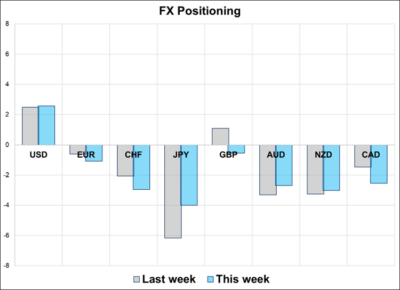
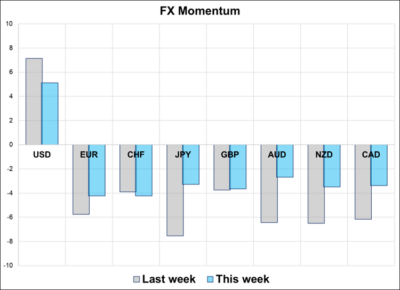
Hi. Welcome to this week’s report. The BOJ and PBoC are doing their best to enforce the double tops in USDJPY and USDCNH respectively. These FX double tops coincide—not coincidentally—with a double top in US 10-year yields. The market has finally gone long USD, specifically against CHF, JPY, AUD, and NZD. Meanwhile, EUR and GBP positioning remains close to flat as fast money and other longs are offset by the always-confusing CFTC longs in both currencies. We continue to be a bit flummoxed by the CFTC GBP long, particularly, as none of the standard CFTC explanations (carry, trend, etc.) explain it.
1. Momentum and positioning have both waned a tad as we hit key levels in many pairs. Fast money and hedge funds continue to have trouble getting excited about long USD while the CFTC’s net looks more like GBPAUD long, GBPNZD long, and EURAUD long. You can see here that prior moments where the CFTC was mega short (as defined, rather simplistically, by -70000 or more contracts).
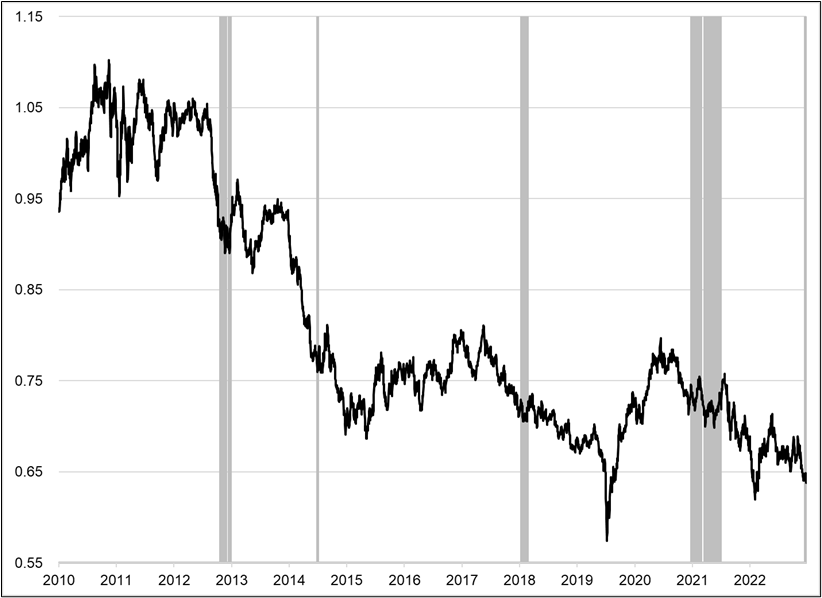
You can see that (similar to JPY), the CFTC is pretty good at trading AUD and when the position is extreme, they tend to win, eventually. That said, they also seem to hit max short right at the nadir before a big squeeze. CPI will decide that more than any positioning metric.
2. Volatility in FX has been bouncing along the bottom for three months. Below is the 1-year chart of CVIX. There is some hope for vol bulls because the CVIX has a seasonal bias to go up in the period from September to December. Still, even recent large moves in USDJPY have not stirred the pot.
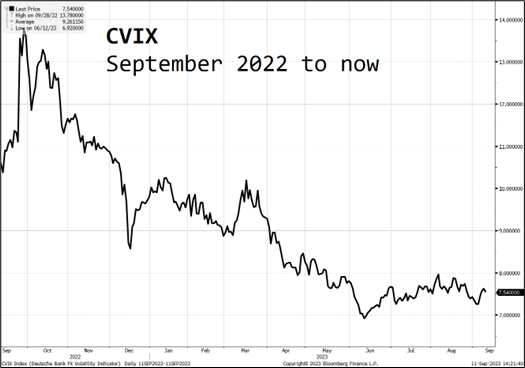
A break of the double top in US 10-year yields (4.34%) is a realistic catalyst for a pop in fixed income and FX vol. You could argue that such a break of the double top in yields will put tremendous pressure on the double tops in USDJPY and USDCNH and may trigger a vol-positive event as everything hits new YTD highs at the same time.
—
That’s this week’s report. Thank you for reading.
https://twitter.com/greg16676935420/status/1700178590761894033
The comments and Greg’s responses below
that tweet are worth 4 minutes of your time. e.g.:


A sort of almost unbelievably large move in Brazil. Plus: Short CADJPY.

NZD has a bunch of bullish kickers: Election, seasonality, and inflation