
A variety of topics today including this week’s calendar, the Fed, Nikkei, AUD, GBP, and USDJPY.


Subscriber-only
Brazil, Canada, yen
A sort of almost unbelievably large move in Brazil. Plus: Short CADJPY.

A variety of topics today including this week’s calendar, the Fed, Nikkei, AUD, GBP, and USDJPY.
Can you guess what aibohphobia and ailihphilia are?
Long USDJPY @ 149.10
Stop loss was 148.14 now 149.14
Take profit 151.15/25
February 20, 2024
The calendar is Thursday-heavy this week as most of the major events come out that day plus NVDA earnings Wednesday night will impact equity prices. Here’s the calendar.
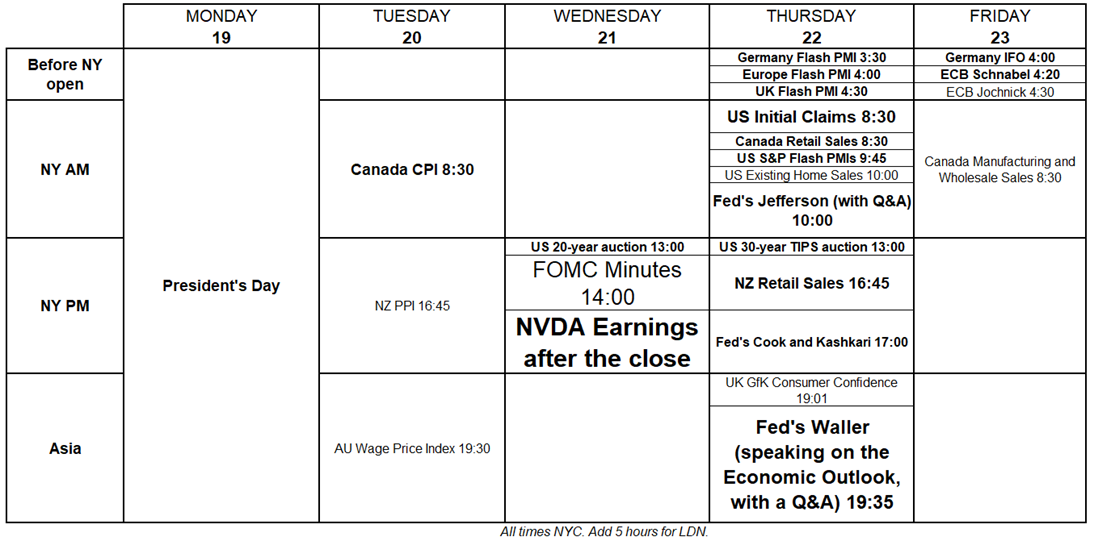
Note Chris Waller, one of the most important voices at the Fed these days, speaks on the economic outlook Thursday night at 19:35 NY time and there will be a Q&A. He was the one that booted off the rate cut excitement overshoot and then reversed it despite what was, at the time, good news on inflation. There’s a bit of confusion in the market as to what the Fed is saying as Waller strongly suggested a spring cut, we got lower inflation, and then he pushed back on it as you can see here.
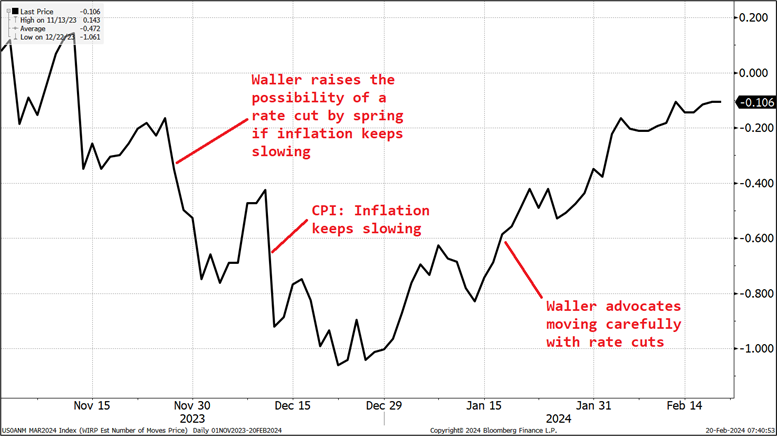
So, I suppose we will see which way the wind is blowing at the Fed with the much less optimistic January inflation data in hand. Thing is, nobody knows for sure if there is a seasonality thing happening with the January data (strong inflation due to seasonal adjustment? weak consumer due to bad weather?), so the February data is likely to be pivotal for the May meeting. March looks like it’s off the table for good.
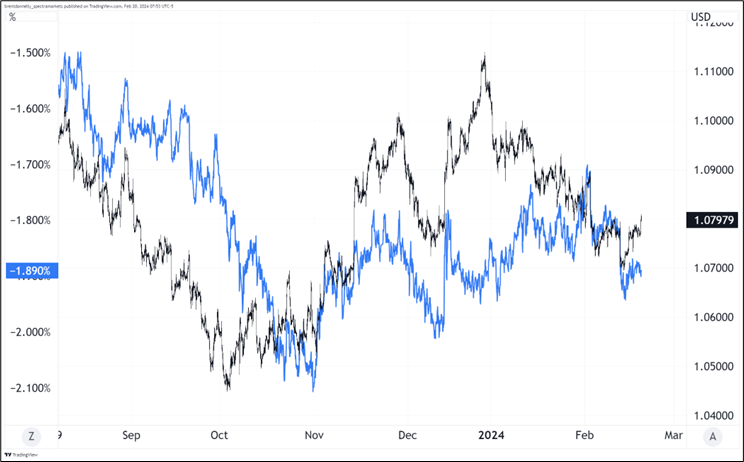
FX remains moribund as changing rate expectations in one country seem to move in tandem with rate expectations in all others and so you have rate differentials for pairs like EURUSD pretty much pegged. This chart shows EURUSD vs. the Germany/US 10-year spread. You can see the spread (in blue) is unchanged since November 2023 and has been in a tight range (-1.75/-2.00). If FX is going to move, it’s going to require some interest rate divergence or a pickup in equity or bond market vol.
An injection of volatility from the equity market is possible as we hit some pretty epic levels of stupidity last week with SMCI, LYFT, and other madness. This Substack from The Shrub does a nice job of covering the major red flags that emerged last week. All these red flags and max stupid just as we enter a negative seasonal period has to be interesting.
In case you missed it in last Thursday’s am/FX:
We are entering a bad seasonal period for stocks. While the last 10 days of February have been up 48.5% of the time, the period has been characterized by some particularly large down moves in 2000, 2007, 2008, 2020, and 2023. As such, the average win is 1.6% while the average down period is -2.9%. The explanation for this could be that New Year flows peter out as compensation and bonus money has been deployed into 401ks and we see some mean reversion as the buying cools off.
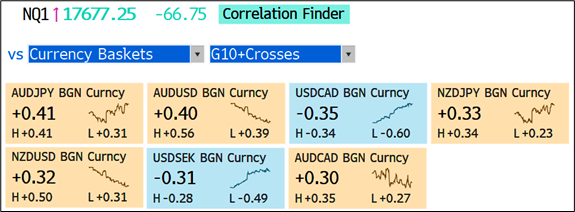
It’s not completely obvious what an equity selloff means for the dollar these days, because it depends why stocks are selling off. If they’re selling off on US growth worries, it’s bearish USD. If they’re selling off on US inflation fear, it’s bullish USD. For the record, here are the highest FX correlations to equities over the past year. These correlations have not been particularly reliable, though. And stocks are down, and AUD is up overnight, so there you go.
I have a friendly relationship with Grant’s Interest Rate Observer and so I am sharing their upcoming event with you because their stuff is always great. If you are interested in Private Credit—here you go!
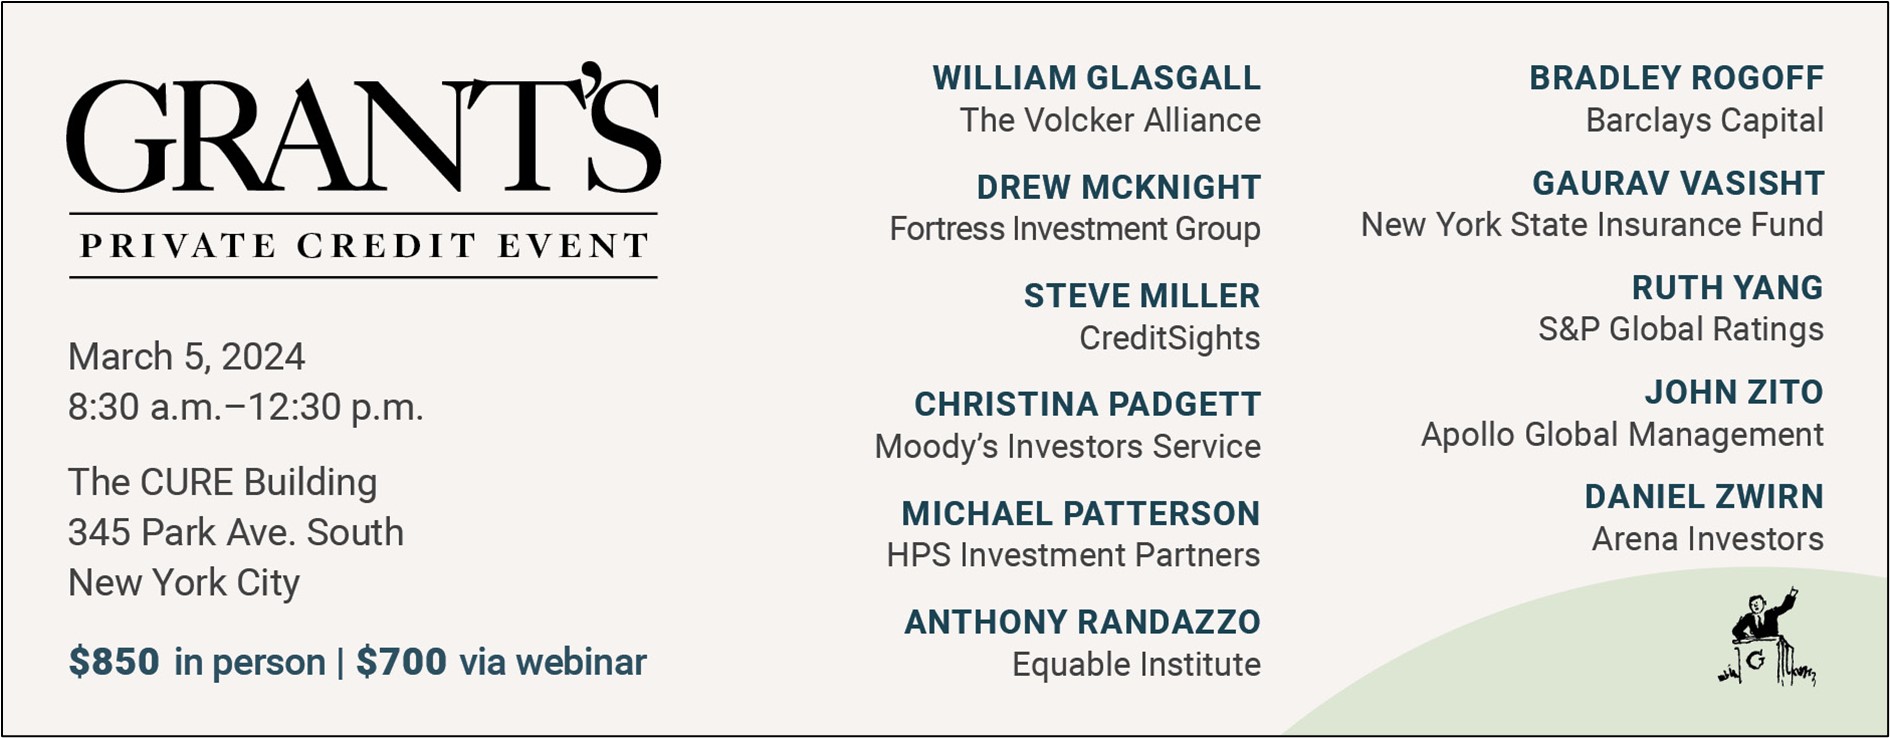
Event Preview: Our long list of speakers is a veritable spice rack of the industry’s leading investors, dealmakers and thinkers. Hear these bright minds, under one roof with you, contribute their unique perspectives on the income opportunity, systemic risks and the cyclical test to come of the enormous $1.5 trillion entity that is private credit.
True to our modus operandi, we will take a hard-nosed approach and evaluate the landscape from every angle. And one of our most pressing questions—”Is private credit in the public interest?”—will be considered in a special panel led by William Glasgall, senior director of public finance at the Volcker Alliance.
Calling this thing a credit event kind of feels like foreshadowing. Spectra Markets received no financial compensation for running this ad, but Grant’s may run an ad for am/FX sometime if they are feeling kind. :]
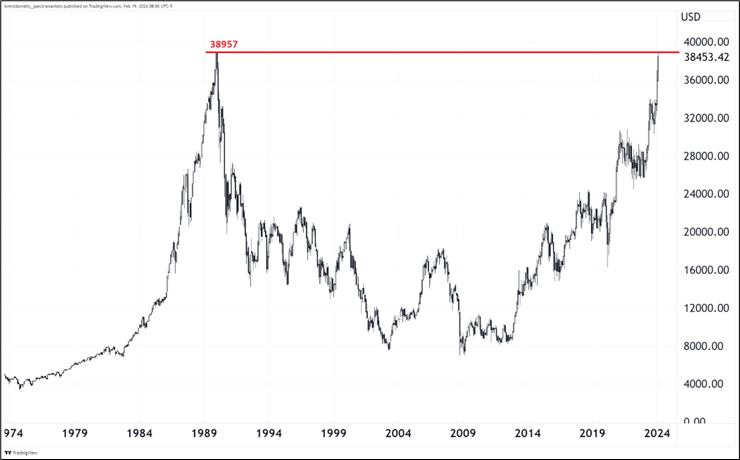
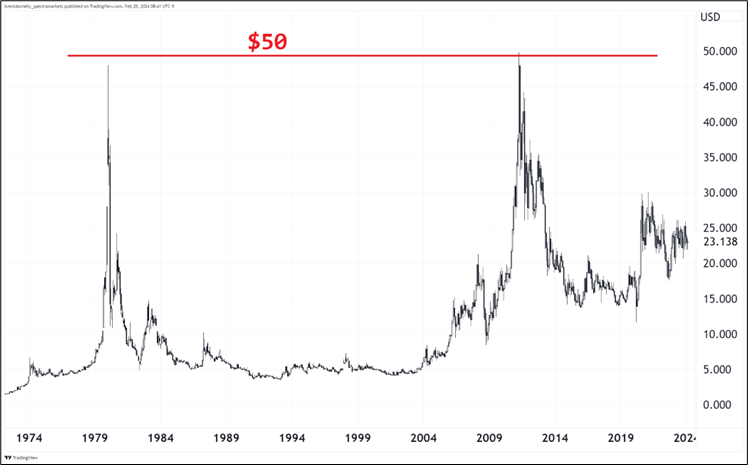
The Nikkei chart is quite a looker! Some will question whether a chart point from 33 years ago matters today but tell that to the people who bought silver at $50 in 1980 and again in 2011. They probably wish they paid attention to the 31-year-old resistance level!
I still lean towards a higher USD as it’s positive carry and vol is low. If stocks swoon on the late-FEB seasonality and/or a NVDA whiff, I can’t even tell you what that would mean for USDJPY or AUD. Selling FX vol and collecting carry is probably still the way for now, at least until we get a narrative or event to chew on. Thursday is obviously the prime candidate for any excitement that might happen this week.
Watch for an extreme print in GBPUSD and AUDUSD today at 11 a.m. NY time as the market is geared up for potential buy flows related to Rio Tinto’s dividends. These flows can be humongous and there is some expectation that they will happen today.
Finally, I am sticking with the long USDJPY trade as the base case is still higher and the thing collects about 16 pips/week of carry if nothing happens. Not chump change!
Have a backwards and forwards kind of day.
SPACESUIT! (I use caps)
Aibohphobia and ailihphilia are the fear and
the love or appreciation of palindromes, respectively.
The words are both palindromes themselves.
HT Gittles
A sort of almost unbelievably large move in Brazil. Plus: Short CADJPY.

NZD has a bunch of bullish kickers: Election, seasonality, and inflation
