The path of least resistance is a higher USD in the short term. This does not mean I am short USD—it just means I think risk/reward is poor on long USD.
Sunset in Northern Maine

The path of least resistance is a higher USD in the short term. This does not mean I am short USD—it just means I think risk/reward is poor on long USD.

Sunset in Northern Maine
August 8, 2023
Hello, I am back from a fishing and economics conference: Camp Kotok in Maine. Given there’s a lot going on in the market, I will publish my takeaways from Camp Kotok in am/FX tomorrow.
Here my market thoughts, in as brief a format as possible:
1. As of 27JUL, I have been bearish megacap tech. This is a multi-month view as I saw many signs of full topside capitulation along with bearish seasonals and way too much weird stuff going on under the hood. Full explanation here. I still think megacap has at least four to six more bad weeks here.
2. Seasonals are working. The historical VIX seasonal bottom is July 19, the worst seasonal periods for AUD, NZD, and GBP run late July into early September, and bullish seasonality for TLT starts right now. Seasonals are just one factor though.
3. The path of least resistance for the USD has been up, and the Moody’s bank downgrades may be creating more upward pressure on the USD as they could create a grab for collateral. Rate differentials are losing a bit of their dominance as the primary explanatory variable for USD direction.
4. I think the combination of Powell and Williams both endorsing the possibility of cuts in 2024 takes the edge off the dollar’s upside. If you are talking about cuts, you clearly believe you are well into restrictive territory.
5. Another reason I am less bullish USD is that 2023 has been all about narrative mean reversion and the dominant narrative now seems to be “US Reacceleration.” The narrative makes sense as ISM New Orders suggest that maybe we’re at the bottom of the manufacturing cycle and GDPNow is printing up around 4%. But each new narrative in 2023 has made sense and yet it never lasts.
Speaking of the wild volatility of the narrative arc this year, you might not remember that going into the March FOMC, eight economists were calling for a cut and one was calling for a 50bp cut and the end of QT. Life has a good sense of humor. You might feel that there is still a large cohort of people calling for recession, and I agree, but this cohort will simply continue to call for a recession until it arrives. Even if that is 2026. This is the danger of the yield curve as an indicator of recession. Yield curve inversion probably costs people more money than it makes them because it offers the worst kind of forecast. Highly certain, with no time condition.
6. A third reason I am less bullish on the USD overall is that it would be highly unusual for the PBoC to fix lower, change some rules, and clearly show a preference for a stable USDCNH at 7.17… And then just give up at 7.25. More likely is that another intervention or rule change is coming somewhere between here and 7.30. You can see in the chart below that at similar levels of rate differentials (blue line), the two main pivots in spot USDCNH were 7.2850 and 7.3760. I mentioned last week that I thought PBoC would lose the first battle, but it’s usually a bad bet to think they’ll lose the war.
USDCNH is set to get choppy, and intervention or rule change probabilities rise substantially above 7.2800. Also note, CNH is weaker against the basket now than it was in October 2022 when the PBoC got serious. And perhaps the new governor of the PBoC wants to show who’s boss? I doubt we take out 7.38.

7. A fourth and final reason that I’m not bullish USD anymore, despite some remaining USD-bullish factors like seasonality, is that I think the Fitch downgrade got under people’s skin a bit and pointed out the potential fragility of the current American policy framework. When interest costs are zero, debt doesn’t matter. When yields are 5% and inflation is 4%, maybe they do?
It’s probably nothing, but the frequency and loudness of commentary and concern about the US fiscal situation going into what’s going to be a crazy 2024 election has risen in the last few days.
I would like for that nervy vibe to subside before I consider long USD again. Just in case some big real money or central bank actors feel the vibes and do another huge sell USD rebalance like we saw in the first half of July. While many countries had similar responses to COVID, few have kept the pedal to the metal like the USA. US deficit to GDP is 8.5% while Germany and Australia (to pick two random examples) are more like 2.5%. Deficits don’t matter most of the time, but when they matter, they matter a lot. I want to make sure we are not entering a regime here where the market has decided they matter.
If you put all that together, and add in US CPI and Retail Sales this week, and then look at where everything is trading chart-wise (look at AUD, for example, right at the bottom of a major range)… I think risk/reward on long USD is extremely poor here and if I had any edge on CPI or Retail Sales, I would be leaning short USD. I will dig into those later today and if I come up with any lean, I’ll tell you tomorrow. While short USD and bearish equities don’t always go together, my equity view is a bit bigger picture and relates more specifically to megacap underperformance vs. equal weighted indexes. And there’s no reason why megacap and the USD can’t go down together.
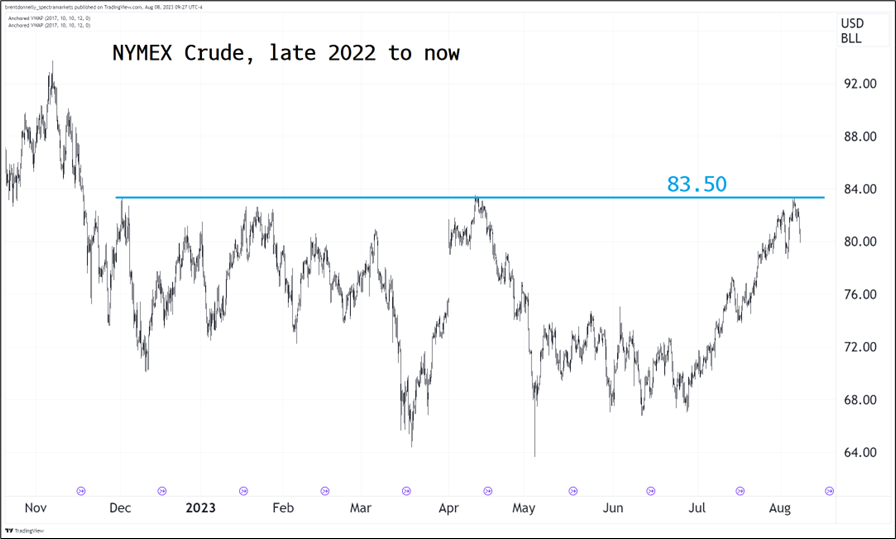
I had been impressed by the rally in oil and gasoline of late, but my conviction is now much lower as CL failed right at the top of the range and RBOB broke down out of the bull flag, instead of up. I thought we were off to the races but now it just looks like the endless range trade continues. Through 84 will be exciting to the topside. Here is the chart:
This article is interesting, but I mostly love the hand-created graphic showing dart locations. Created by hand after watching video footage! That’s good reporting.
https://www.nytimes.com/2023/08/05/upshot/darts-sports-perfection.html
Jackson Hole! “Structural Shifts in the Global Economy.” No agenda yet; it usually comes out in the days leading up to the symposium.
https://www.kansascityfed.org/research/jackson-hole-economic-symposium/
Have a beautiful, colorful day.
The Spectra FX Positioning and Momentum Report
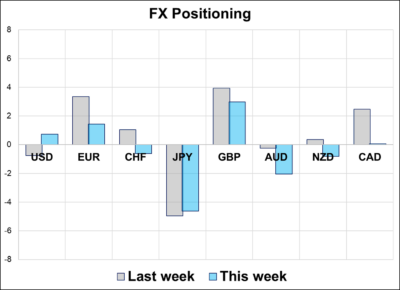
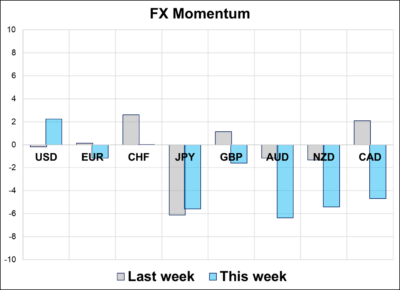
The market has trouble getting excited about USD upside and is very slow to get involved. While spot traders will happily ride the USD rally waves, structural participants seem rather averse to committing to a strong dollar. Maybe it’s about where we are in the Fed cycle (near the end) and the large structural deficits looming overhead.
The only notable positions remain the short JPY and long GBP, mostly via CFTC. And many readings of equity positioning are finally showing full capitulation from mega short at 3500 to somewhat long at 4500.
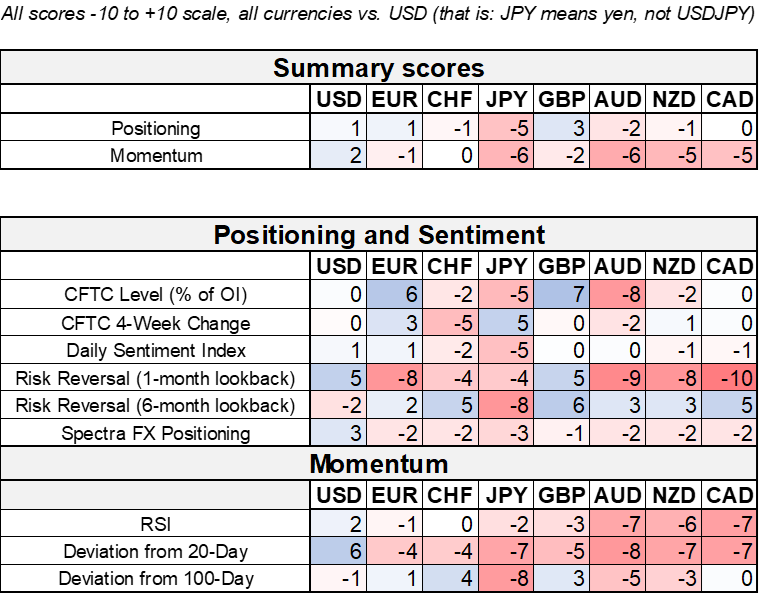
That’s this week’s report. Thank you for reading.
Sundown Downeast Maine

This piece is mostly for people who are interested in backtesting