Today’s note details my plan to sell USD on any further rally.
Francis Bacon
What has been will be
again, what has been done
will be done again.
There is nothing new
under the sun.
Ecclesiastes 1:9

Today’s note details my plan to sell USD on any further rally.
Francis Bacon
What has been will be
again, what has been done
will be done again.
There is nothing new
under the sun.
Ecclesiastes 1:9
LIMIT ORDERS (NOT YET EXECUTED)
Sell USDJPY at 136.94
Stop at 138.33
Buy EURUSD at 1.0588
Stop at 1.0464
Buy NZDUSD at 0.6141
Stop at 0.6039
February 28, 2023
I expect minimal fireworks for month end as stocks are only down 1.8% this month and half of Wall Street is getting out the Play-Doh for a snow day. USDJPY is entering the interesting zone and European rates are on the move.
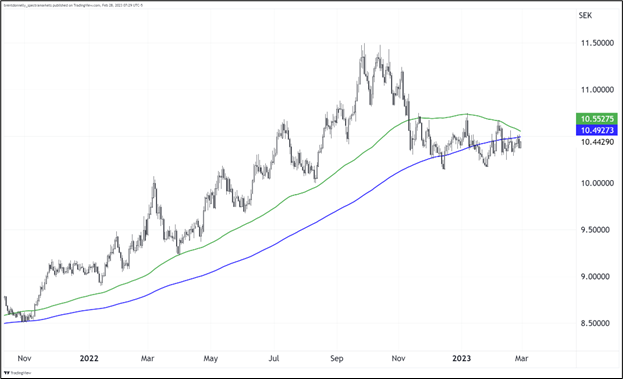
Every chart is getting towards a huge level. Here’s USDSEK, for example:
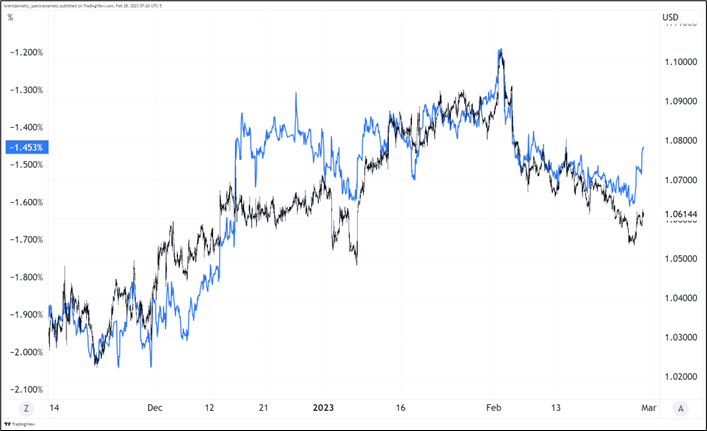
And of course, USDJPY:
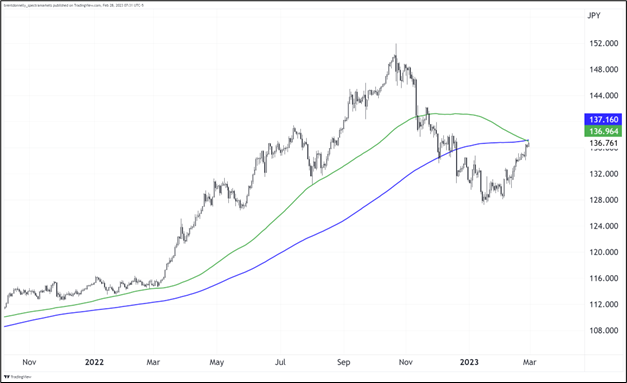
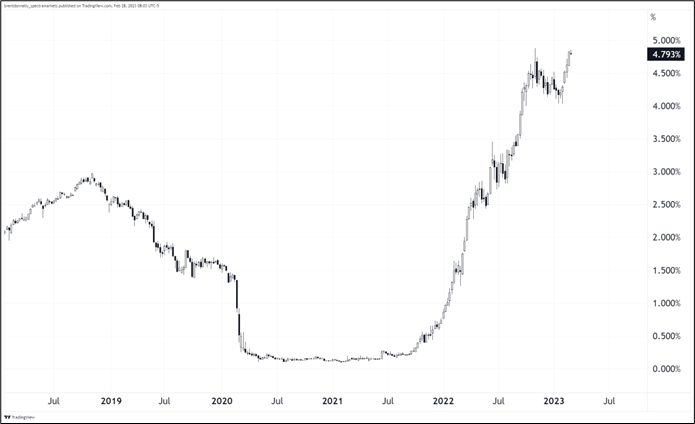
As discussed in detail yesterday, I think the USD rally runs out of steam as the Great January Data Surge is unlikely to show acceleration in the February data. 2023 is a year to focus on mean reversion. The moves higher in the USD and lower in stocks have been super orderly and while one could argue that fear is right around the corner, my view is that the market is absorbing the higher terminal rate without much angst and that’s probably constructive for now. Sure, things might break at some point, but they are not breaking yet[1].
I don’t have a particularly strong view on ISM tomorrow but the lead indicators point to something either close to, or a bit above expectations. Still, global rates are going up faster than the US and volatility is under control. Fixed income, FX, and equity volatility are not reacting much to the higher terminal rate in the US and that’s a sign to me that risky asset scaffolding is solid and there are no severe cracks below the surface right now.
There is a particularly notable dynamic in FX right now where we have seen a 5% selloff in Kiwi and friends and yet FX vol has not gone up and the market is not bid for NZD puts. That is unusual. There is a full discussion of this dynamic in today’s Positioning and Momentum Report (see pages that follow am/FX). Check it out, as I think it’s interesting and it’s a good example of how this entire repricing in rates and the USD has been Not Scary.
Here are the trades I like:
Sell USDJPY at 136.94 with a stop at 138.33
Chart has mega resistance 137/138 and I think Japanese real money will be big sellers in that zone. The BOJ turn story is not dead, just slow.
Buy EURUSD at 1.0588 with a stop at 1.0464
German rates are going up faster than US rates. Bottom of the range in EURUSD. Hoping for a random move into month-end to get the trade on. You could do short USDSEK too, but I’m a bit worried too many people have piled into the Riksbank strong SEK theme. Still, I strongly considered it. Riksbank credibility is strong and the policy is new.
Buy NZDUSD at 0.6141 with a stop at 0.6039
China reopening trades have capitulated and copper bouncing. Major support 0.6050/70. NZD down / vol down is bullish (see today’s Positioning Report).
I am hoping for a bit of noise today to get these things on and the dream is to ride them right into weak CPI on 14MAR. All three trades are in the sidebar. It’s possible I miss them all by trying to thread the tactical needle, but I would rather aim for optimal entries and avoid the temptation to just sell USD here at arbitrary levels. There will be noise around today’s month end and then noise around ISM tomorrow, so I have two possible chances to get set.
—
[1] A single subprime auto company bankruptcy has given bears a small frisson of excitement but I doubt that is sufficient to ring any alarm bells. The entire subprime auto lending market in the USA is $20B.
Here’s a summary of my USD bearish thesis:
Have a salty day.
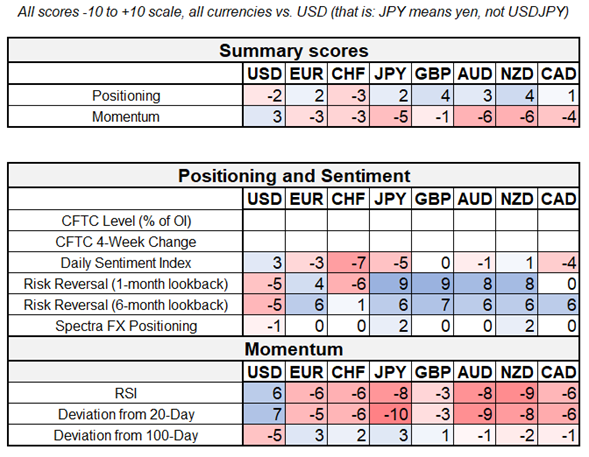
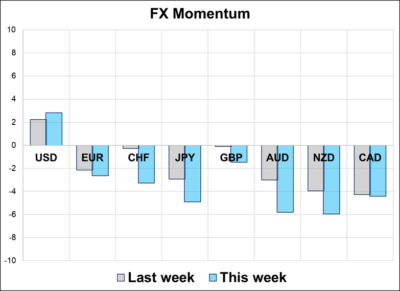
Positioning is light overall as the narratives around USD down, China reopening, ECB normalization, “Fed won’t hike above 5%”, and “The UK is toast” narratives have all withered on the vine after early 2023 excitement. Now, the market is scraping together narratives a few days at a time based on the latest US data or Fed talk. For now, the narrative is rising risk aversion and a stronger USD on higher yields but participation is minimal because the narrative snuck up on everyone and entry points don’t look attractive. So here is where it’s at:
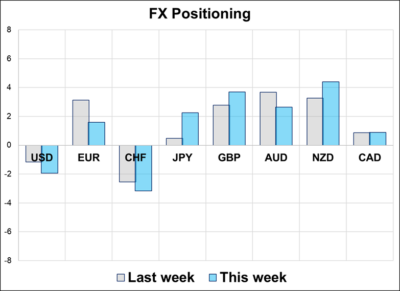
1. The CFTC still can’t get their big numbers machine to work so there is no CFTC data again this week.
2. The market is just not that interested in trading long USD. The bias is strong and most speculators are just sitting out this dollar rally as they believe that short USD is the trade you want to own for the most upside while long USD is a rental, at best. There is plenty of dry powder if evidence appears to indicate that January’s Blockbuster US data surge was a mirage.
3. An interesting development over the past month has been the fall in NZDUSD with no concomitant rise in NZD vol or change in the risk reversal. This is what you might describe as a “not scary” move in NZDUSD and risky assets. They are selling off but vol is tame and it’s not scary.
This is similar (but opposite) to a setup I always point out when it happens: VIX UP, SPX UP. That should not normally happen and it’s a strong indicator that something weird is going on (bearish). In this case, the fact that Kiwi is down 5% and vol and skew have barely moved (vol is down a bit and skew is slightly better bid for calls) is a sign something weird is going on in the other direction (bullish). The sample size leaves a bit to be desired but here are the returns on the nine prior occasions we saw this unusual dynamic.
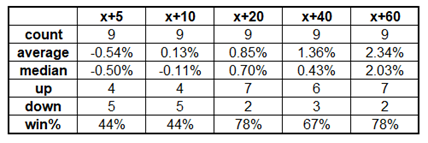
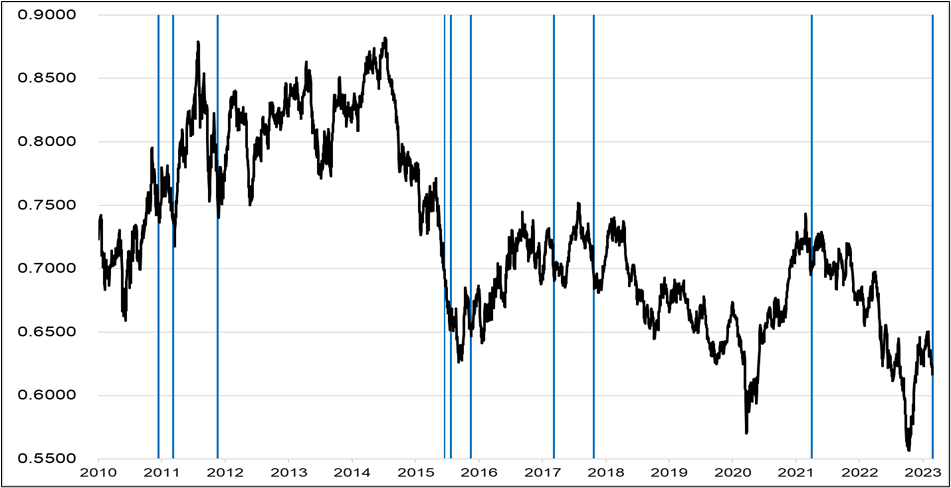
So this dynamic tends to happen near bottoms but is not a perfect timing signal. The next chart shows the times it happened. A quick glance shows you most of the time this condition is met just before v-shaped bottoms. 2015 is a significant exception as the China deval was happening at that time and if you take out that one event (NZD was down more than 10% 60 days later) you get 60 day returns of +3.7%. This is information you should treat with great caution. A sample size of 9 is already small. Taking out the worst performing moment leaves you a biased sample of just eight. Still, I think it’s informative that the baseline after these things is NZD rips higher. The exception was a July signal where a major shock a month after the condition was met cratered Kiwi.
And finally, while again I would stress a sample size of nine is rather limited, here is the average path of NZD over the 60 days after this condtion was met.
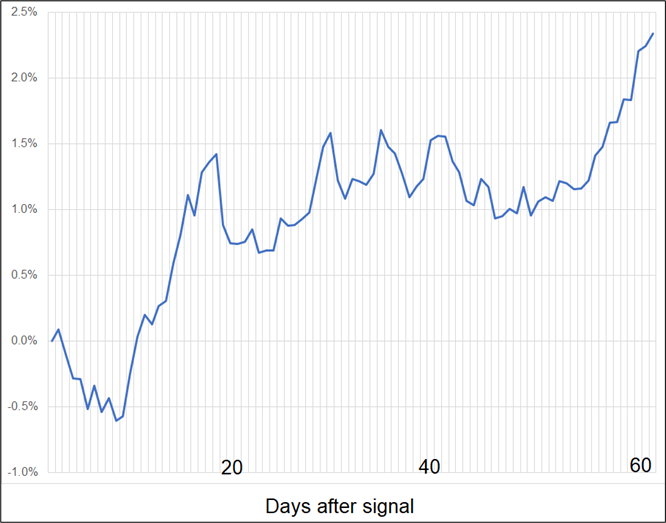
I would not normally write about a study with a sample of nine, but in this case the logic of the output matches the VIX UP/ SPX UP logic perfectly and thus I think I can infer some amount of signal despite the small sample. If the options market is not confirming what’s going on in spot, there is probably information there. In this case, the information is that despite the selloff in risky assets, options market are not scared. This is consistent with my overall observation in am/FX: Not Scary… Markets have calmy repriced the higher US terminal rate. They are not freaking out.
That’s this week’s report. Thank you for reading.
From Tyler Cowen:
Francis Bacon’s critique of the printing press focused on four main points:
– First, he argued that the printing press had flooded the world with too many books, especially of ancient and scholastic learning, that were either obsolete, irrelevant, or misleading for the pursuit of true knowledge.
– Second, he argued that the printing press had encouraged the idolatry of books and authors, as people tended to accept the authority of printed texts without examining their merits, sources, or methods.
– Third, he argued that the printing press had hindered the advancement of learning by promoting the imitation and repetition of old opinions, rather than the invention and experimentation of new ones.
– Fourth, he argued that the printing press had fostered the dissemination of false, frivolous, or harmful knowledge, such as superstitions, fables, libels, and scandals, that corrupted the minds and morals of the readers.
—
Sounds familiar. Maybe society will figure out this whole toxic and destructive social media problem, eventually.


A sort of almost unbelievably large move in Brazil. Plus: Short CADJPY.

NZD has a bunch of bullish kickers: Election, seasonality, and inflation