Talking about yields, USDJPY, the US economy and more.
Plus a fun and upsetting excerpt from Ben Hunt’s Epsilon Theory.

Talking about yields, USDJPY, the US economy and more.
Plus a fun and upsetting excerpt from Ben Hunt’s Epsilon Theory.
After a chance encounter with a
chicken while on vacation, fine
art photographer Alex Napel
was inspired to focus on
chickens in his work.
Long USDJPY @ 132.00
Stop loss 130.74
Take profit 134.69
Long USDCAD @ 1.3393
Stop loss 1.3279
Take profit 1.3644
Long 07FEB EURGBP call
spread 0.8870/0.8920 risking
22 GBP bps to make 50
Spot ref. 0.8850
February 6, 2023
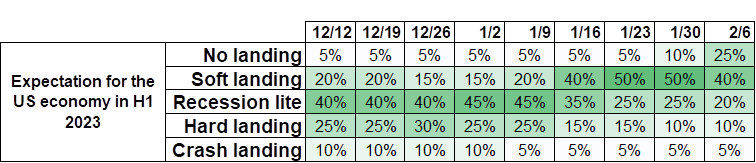
Happy Monday. In am/FX: Five Main Outcomes, I talked about a probabilistic approach to 2023 as there are so many paths this US story could take this year. Normally, the decision tree on the economy has just a few realistic branches, especially during the low economic volatility secular stagnation regime from 2011 to COVID. Now, the economy could pretty much go anywhere and it would not be a massive surprise.
Here is my assessment of how the market odds of the five main outcomes have evolved over the past two months:
I discussed this and more in a 30-minute RealVision spot with Maggie Lake on Friday afternoon. Welcome new subscribers who signed up based on that interview! Feedback, questions, and criticism are always welcome.
Friday’s NFP data was consistent with low Initial Claims and both continue to show historic tightness in the labor market. Meanwhile, the exaggerated weak sentiment and soft data from December is mean reverting in January with borderline ridiculous bounceback moves in series like ISM Services New Orders last week. I have been saying for a while and continue to believe: Trust the hard data and not the soft data in this cycle.
I am surprised how little USDJPY has rallied with Amamiya leaked in the Nikkei last night, and yields ripping higher in the US as the market capitulates on H1 recession calls. Maybe part of it is just that the Nikkei story was not confirmed by policymakers and so the market is not ready to fully believe that Amamiya is going to be in charge of the BOJ in April. My bias is always to believe the leaks in Japan as their accuracy is high.
Here’s USDJPY vs. US 10-year yields:
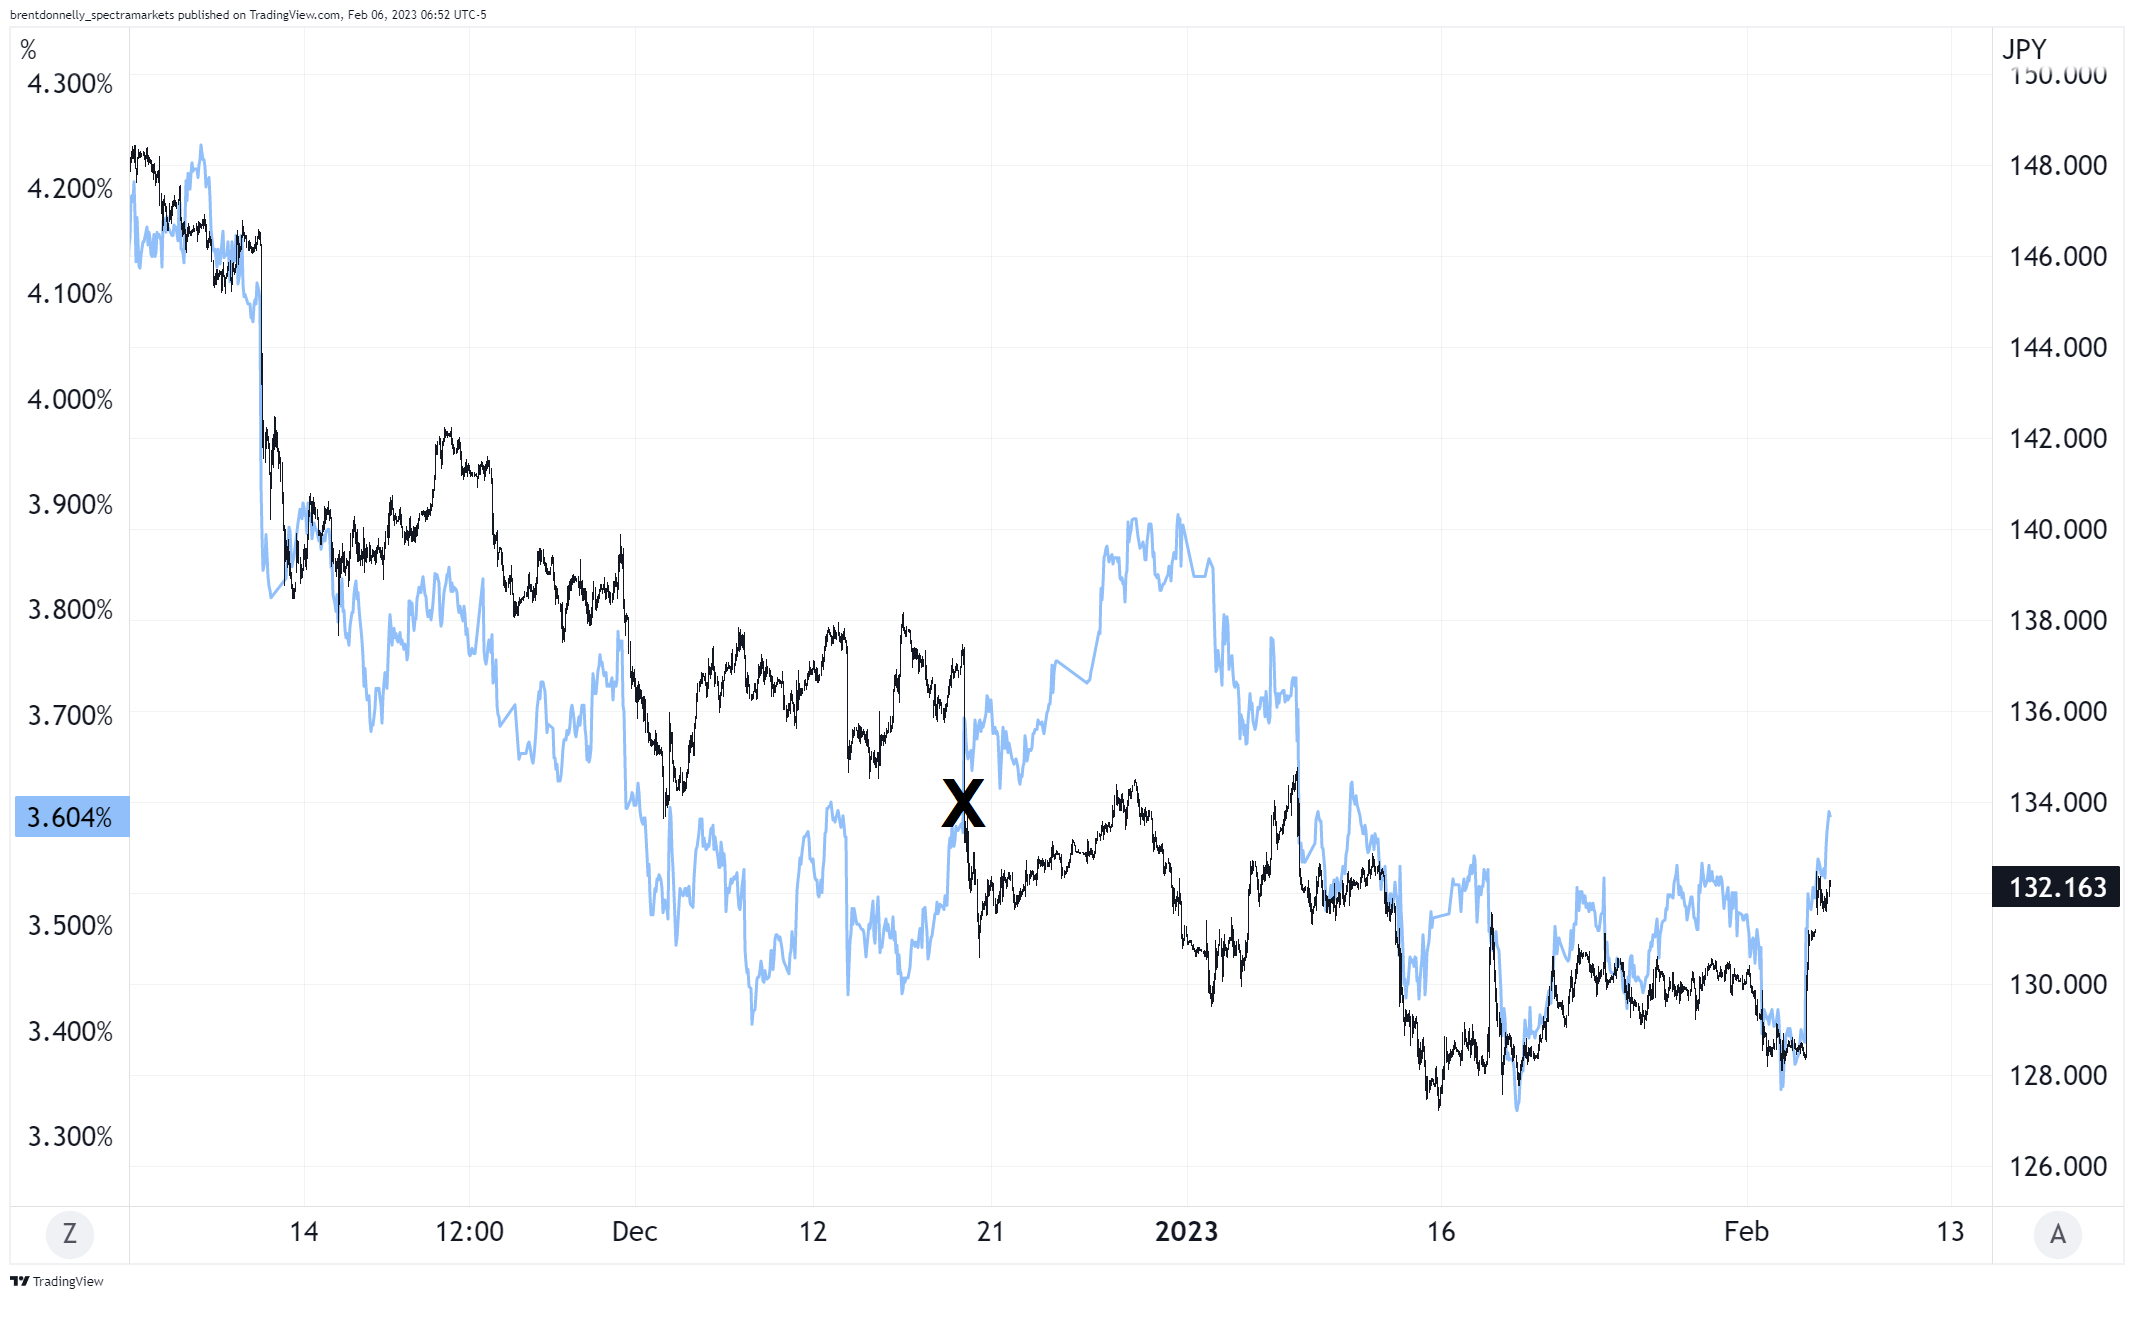
The X on December 20 marks the day the BOJ raised their 10-year yield cap. This day saw a jump in global yields and a fall in USDJPY and that’s why the lines move the opposite directions there, but you can see that the correlation rapidly returns to normal and is back to steady and reliable where US yields up = USDJPY up.
With higher spot inflation coming in the January data, Powell speaking today after the hot jobs number, and yields already causing pain at 3.60%… I like USDJPY and US yields higher over the next week or so. While the price action is anything but explosive so far, it is encouraging that it has held the Sunday gap perfectly as you can see here:
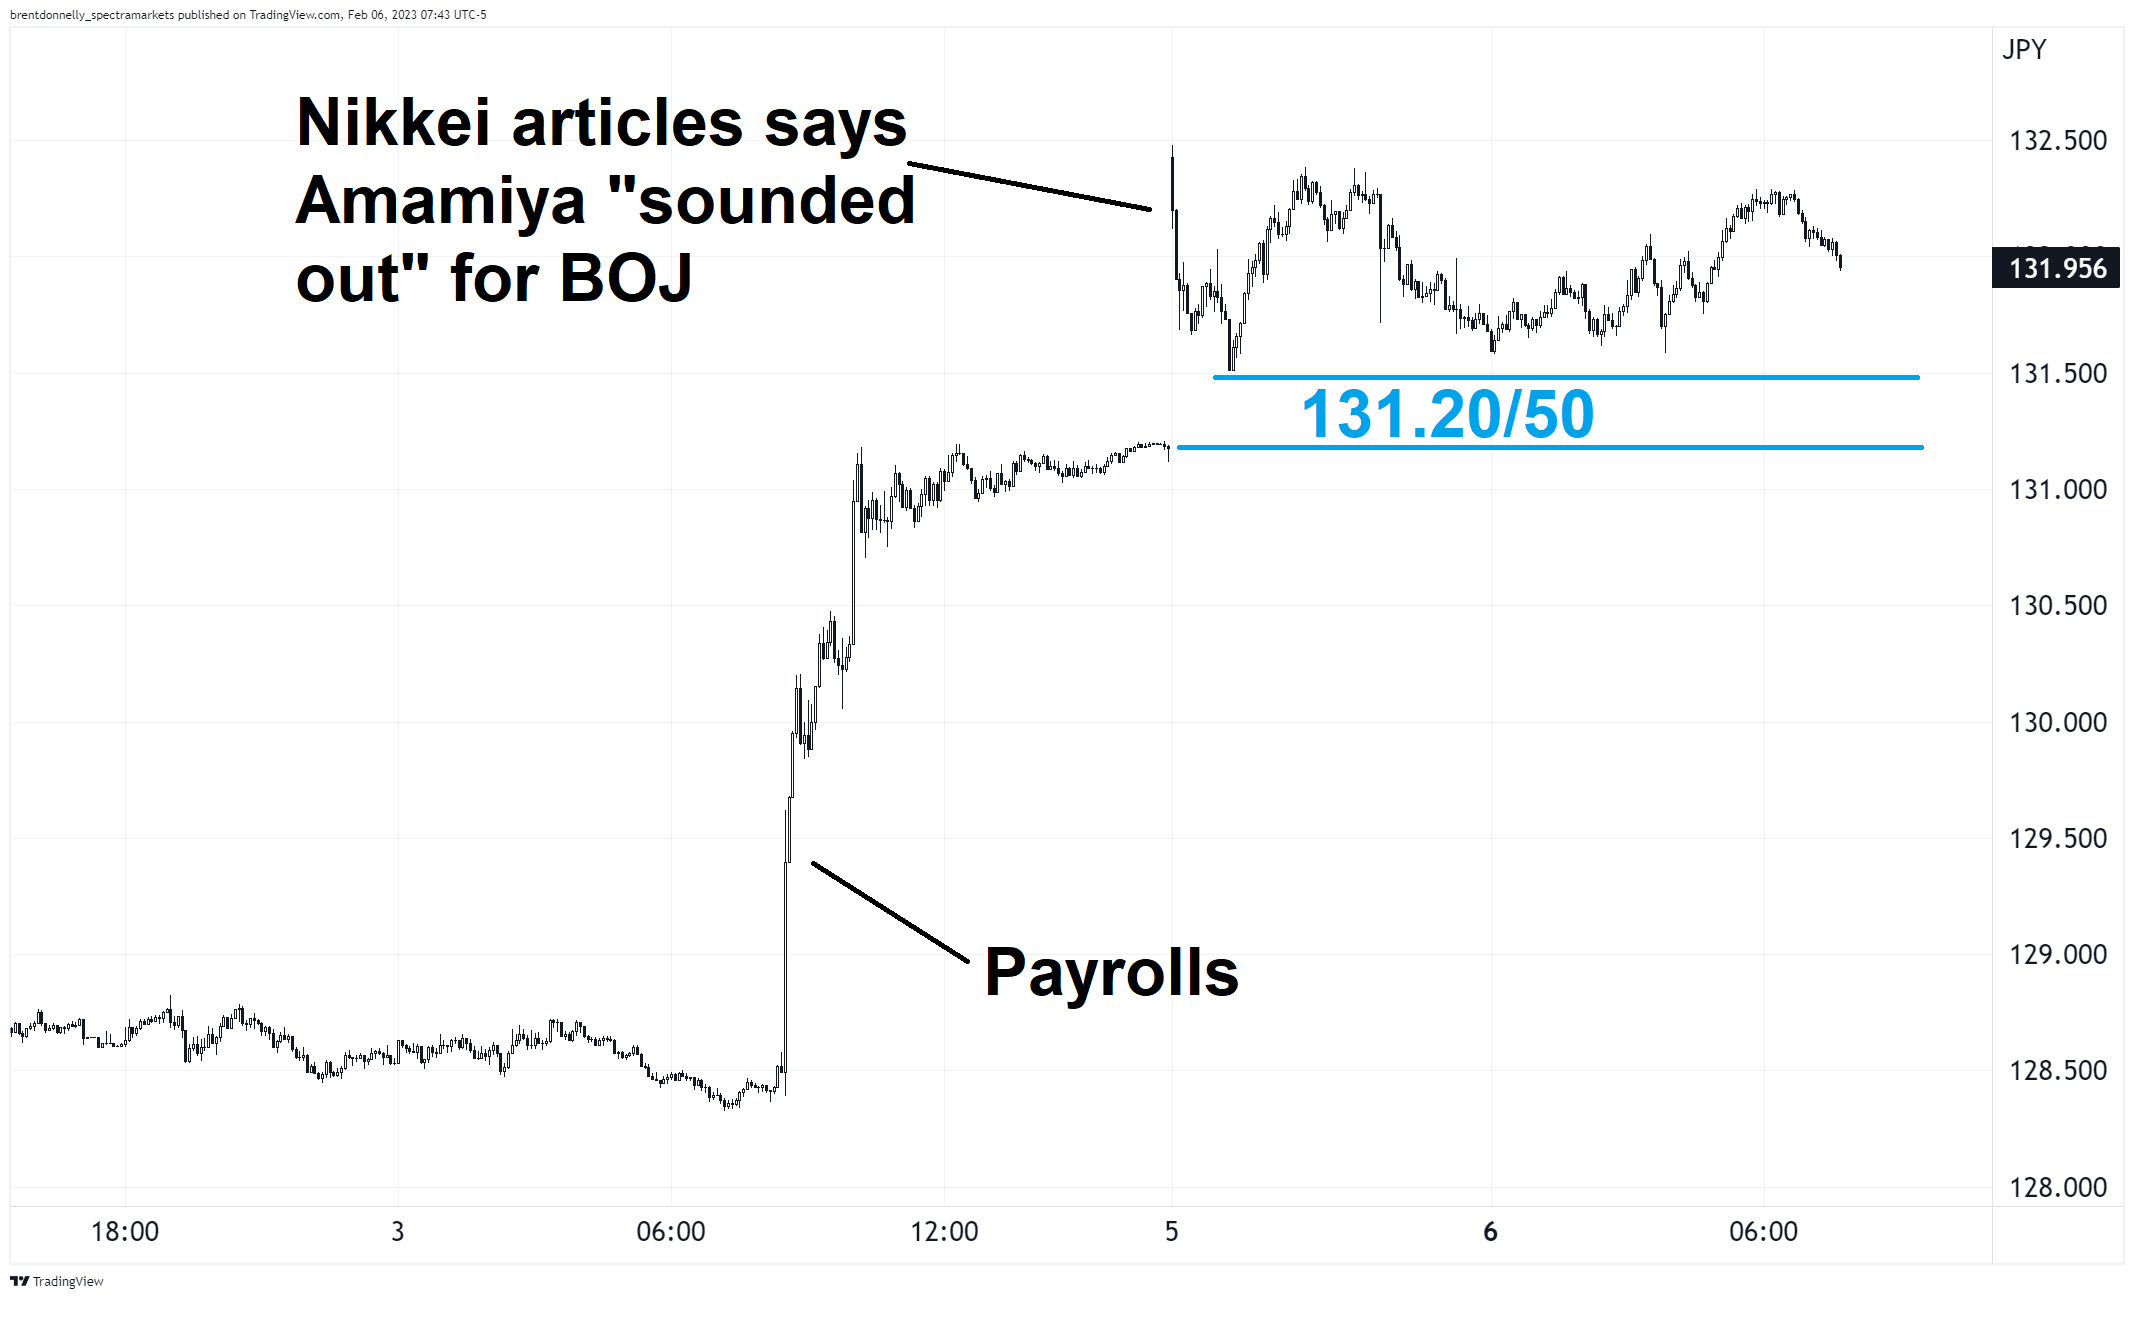
As long as USDJPY is above 131.00, I’m bullish. I am going long USDJPY here (132.00) with a stop at 130.74, looking for 134.69. Risking 126 to make 269.
The NZDCHF take profit hit overnight. That was a good trade as NZDCHF failed to rally when stocks were going up and then fell when stocks went down. Weak NZ data, which was part of the thesis, also helped.
The EURGBP call spread expires tomorrow. It’s always a tricky situation when a call spread goes through the top strike. Do you hold on and try to extract the last few pips of positive theta? Or do you cut it so you don’t have the negative asymmetry on the mark-to-market if it tanks? In this case, I think the EV is positive to keep it and wait for expiry at 10am tomorrow. But of course there is a major risk of regret here as most of the P&L has been realized and yet all can be lost if EURGBP were to tank back down to 0.8870 overnight.
The USDCAD bid was filled at 1.3393 and that trade makes a lot of sense to me given my views on risky assets, yields and given oil is doing its “I can’t rally no matter what!” thing again.
For many years, I have believed that Epsilon Theory is the most consistently useful thing I read. Period. It’s the best way to rationally understand our current mixed-up world and it offers the most useful framework for analyzing geopolitics, politics, society, and the economy. In case you missed it, the January 22 note “Yay, College!: The smiley-face super-villainy of American higher education” is a fantastic and eye-opening read. It resonated with me both as a parent of a child in university, and as a person that has hired many recent university graduates over the past 10 years.
The whole system is designed to extract more and more money so it can build larger and nicer buildings, serve fancier, more luxurious food, and employ thousands of overpaid bureaucrats in pointless administrative roles. Here is an excerpt (with permission) that captures the ludicrous post-secondary overspending enabled by cheap government financing.
As for the expansion of the ecclesiastic administrative class … I’m sure everyone has read an article or heard a suitably shocking anecdote about how many administrators there are at colleges and universities today, and how well paid they are. For example, one recent article making the rounds was about Yale now having a one-to-one ratio of administrators to students. Not faculty to students, that ratio is basically unchanged for 30 years except that much more of the instruction is done by graduate students and not faculty at all, but administrators to students.
But hearing these anecdotes doesn’t prepare you for the full scope of what’s going on.
Here’s a link to the Fall 2020 list of employees and salaries, organized by department and office, for the University of Florida, our fifth largest single-campus public university with 58,000 students. This document is 1,035 pages long. That is not a typo. The list of University of Florida employees is one thousand and thirty-five pages long.
Every page looks something like this, the personnel and salaries associated with the Office of the President (President’s Office), not to be confused with the Office of the President (Chief Diversity Office) or the Office of the President (Office of Internal Audit). And on every page there’s a surprise.
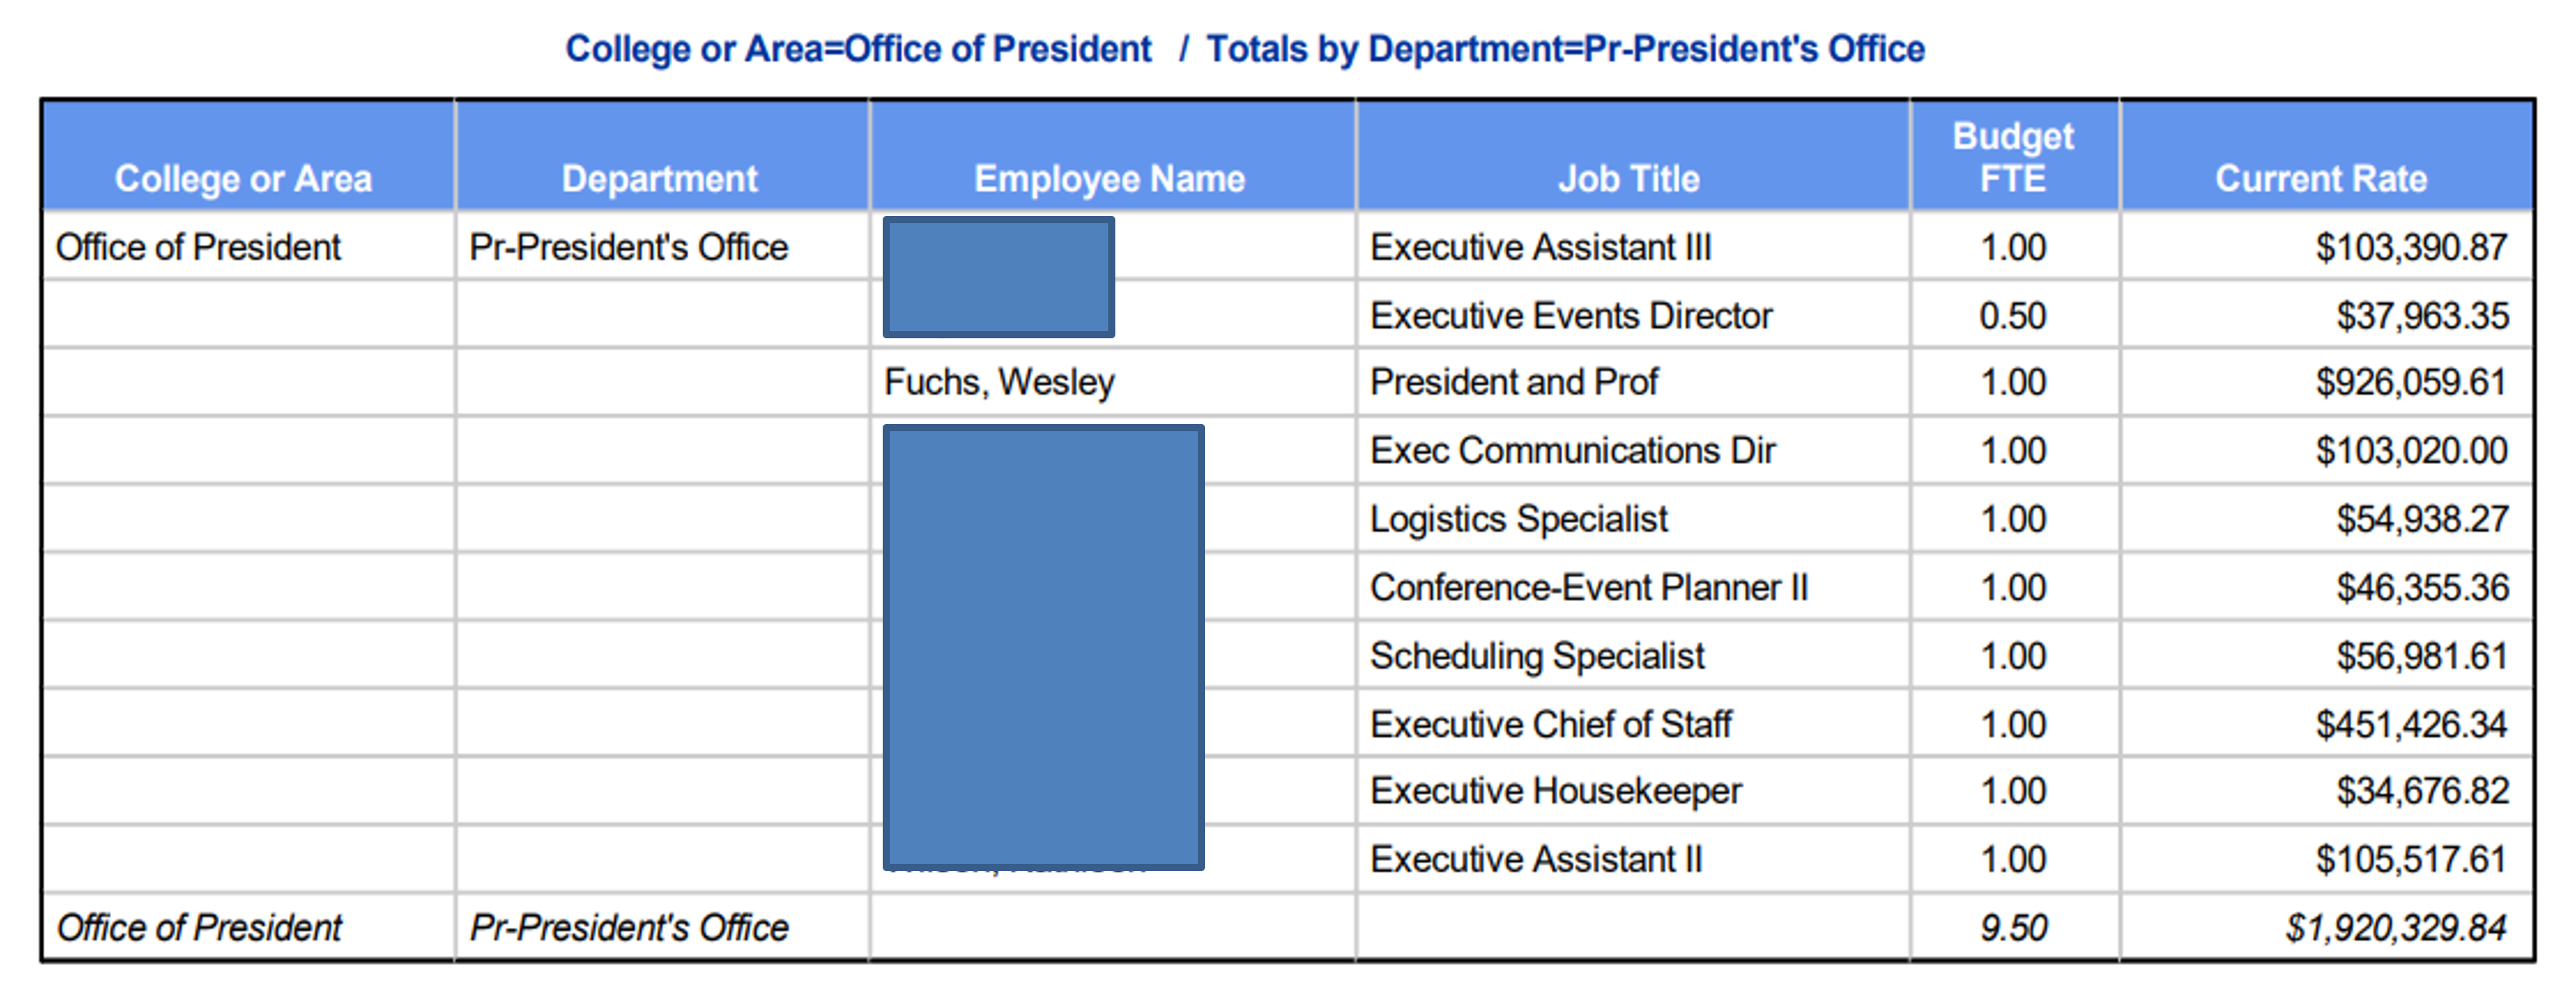
Like, it’s surprising to me that the Office of the President (President’s Office) has not one but two executive assistants who make more than $100,000 per year. Or that the Office of the President (President’s Office) requires a Scheduling Specialist, a Logistics Specialist, a Conference-Event Planner and an Executive Events Director, separate from the other 47 Conference-Event Planners and Managers I found located in other departments. Perhaps most disappointing was that the Executive Housekeeper makes less than $35,000 a year. But these numbers don’t include benefits and bonuses, so maybe it’s not as dire as it seems for the Executive Housekeeper. Certainly President Fuchs can’t complain about the additional $500,000 he received in benefits and bonuses above and beyond his $926,000 salary.
I think my favorite page, though, was this one for the VP of Governmental Relations (Vice President Office), not to be confused with the dozens of Public Relations administrators found throughout the rest of the university. This is an office of 11 people, averaging about $140,000 per year in salary, and they are the lobbyists for the University of Florida.
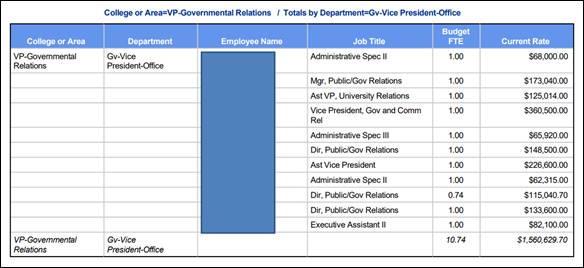
I could go on all day. The Advancement Office has 157 full-time employees. These are the people charged with securing donations from alumni. The Office for Strategic Communications and Marketing has 18 full-time employees. I’m not entirely sure what this office does. Is it separate from an Office for Tactical Communications and Marketing? I dunno.
But I do know this. The University of Florida has a lot more pretty buildings and a lot more administrators than it did 20 years ago, and the tuition for the University of Florida, both in-state and out-of-state, has tripled over the past 20 years.
Just like every other college and university.
Team Transitory loves to look at 3-month annualized inflation when it’s falling, but note January MoM is looking like 0.5% again. Disinflation is here but the rate of disinflation could be disappointing for those expecting a speedy return to 2%.
Don’t be a chicken today.