The Fed is desperate to hike, but the data refuses to cooperate.
“The unsuccessful self-treatment of a case of Writer’s Block”
Larger version at bottom of page
The Fed is desperate to hike, but the data refuses to cooperate.
“The unsuccessful self-treatment of a case of Writer’s Block”
Larger version at bottom of page
31JUL 1.3500 GBPUSD call
22bps off 1.3410 spot (new trade)
10SEP CHFJPY put spread
199/196 for ~37bps off 200.50 spot
30JUL USDMXN put fly
17.40/17.15/16.90
1X2X1 for 30bps off 17.52 spot
I suppose one could argue that Warsh’s dislike of forward guidance is supported by the moves in the past 24 hours. By publicly pinning his vote for a July hike on a single data point, Waller created a burst of unnecessary volatility in markets and may have confirmed what Warsh fears: Forward guidance just moves the volatility around and distorts market signals. Regardless, the real story is that somehow inflation has cratered and the market is still priced for Fed hikes.
Sure, they might still hike, but now we have months and months of data to chew on before the September 16th meeting and by the time that rolls around, we could be priced for zero hikes and finally the end result is they cut in March 2027. There is no smoking gun for a rate hike and July should be priced down to zero now.
But in the interim, you got this:
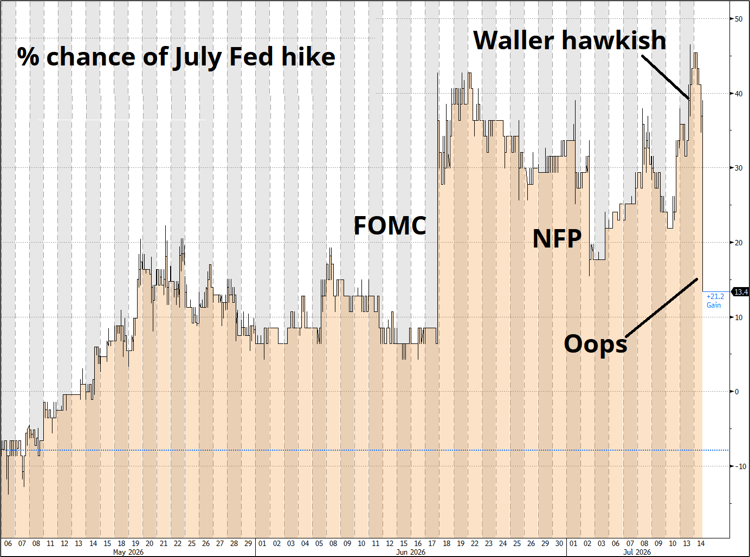
The Fed has shown it is desperate to flex some credibility with a hike, but the data just absolutely refuses to cooperate. Despite the hawkish lean (as evidenced by Warsh 17JUN and Waller’s urgency yesterday), it’s very difficult to justify a hike if you are data dependent. At some point they may find a sequence of releases to justify a hike, but that is not going to happen before September now because the only remaining data points on labor or inflation between now and the July FOMC are PPI (biased lower because CPI already showed the way) and Initial Claims. Core PCE comes out after the Fed meets.
I see today’s CPI data is unambiguously bearish USD and bullish risky assets, and I don’t think the recent escalations in Hormuz will change the landscape. This could be naïve / complacent but the reality has been that you cannot trade war headlines anymore. The start of the war was bullish USD, and the end of the war was bullish USD—there is no coherent framework for trading the war vs. the USD.
Risky assets like silver and semis should also do well as they have been crushed for weeks and the weak longs are all long gone. I would suspect Korean equities even find a base here as the scary prospect of some kind of raging Fed hike cycle is off the table for a long time. VIX back to 15 and SPX new ATH by end of July would make sense to me. I really like the USDMXN structure I have had on and if I were adding USD shorts, I would look at GBP, CAD, and HUF.
GBP is particularly interesting as demand is relentless and the worst case for Chancellor (Miliband) is already priced in. If Burnham were to select someone more market friendly early next week, GBP could rip even more. It is tracing out a head and shoulders with a neckline at 1.3500 and I am going to add 31JUL 1.3500 calls for around 22bps to the sidebar. If you are trading spot, I think you go long here (1.3410) with a stop loss at 1.3274.
RBC FX Strategy made a nice chart showing USD correlation to various crosses. It’s good to know that if you’re trading say, CADSEK, you’re really just trading USD. If you don’t know the USD beta of the crosses you are trading, you are not fully cognizant of your risk or what you are cheering for.
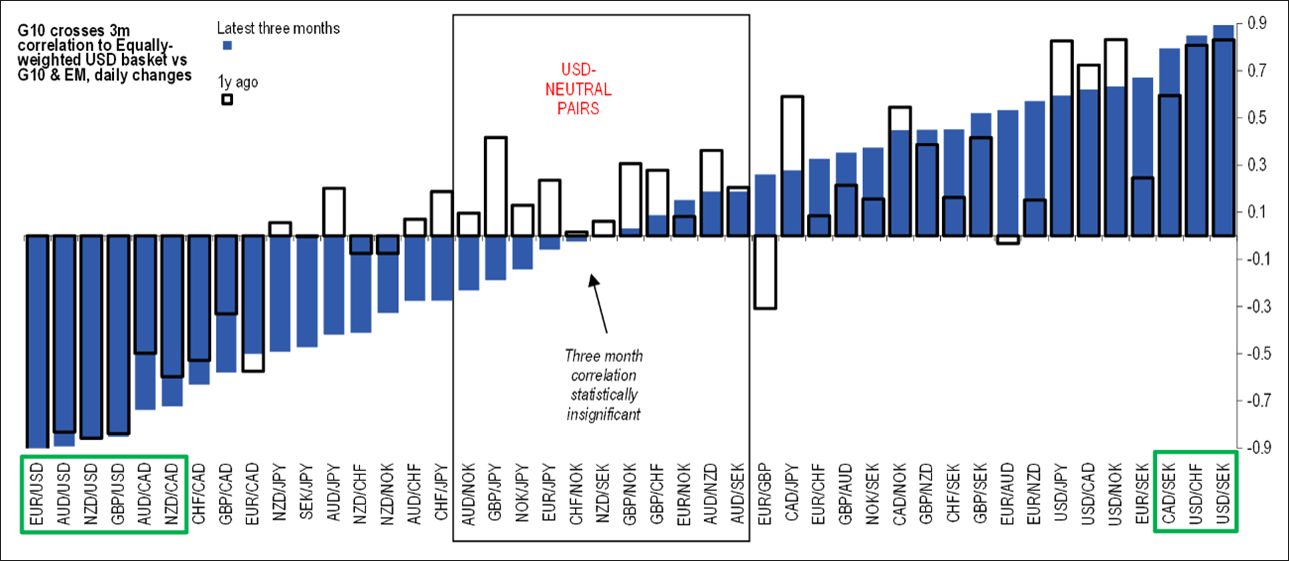
Now (blue) vs. one year ago (white box)