June 23, 2023
Inevitable Eventuation
For the nth time in the past 24 months, the market is in the mode of: Central banks are hiking enough to hurt, and the soft data is looking really bad. The BoE plus Norges combo along with the steep drop in Eurozone PMIs has created the familiar smell of central banks “hiking into weakness.”
It almost feels preordained that this outcome will eventuate, eventually, because if the weakness doesn’t arrive, the central banks hike more. This is similar to saying the Fed will eventually reach its inflation target. As discussed last week, if you can’t attach a timeline to your forecast, the forecast is worse than useless. While price action in GBP was disappointing on the unexpected 50bp hike, the price action in NOK has been borderline cataclysmic. NOK continues to show looney tunes asymmetry as it either grinds lower or explodes higher and refuses to follow orthodox correlations to yields, oil, or risk appetite.
This is an eye-wateringly bad 2023 performance from the NOK in a year where EURNOK still maintained a negative correlation with the S&P 500 and NASDAQ (!!).
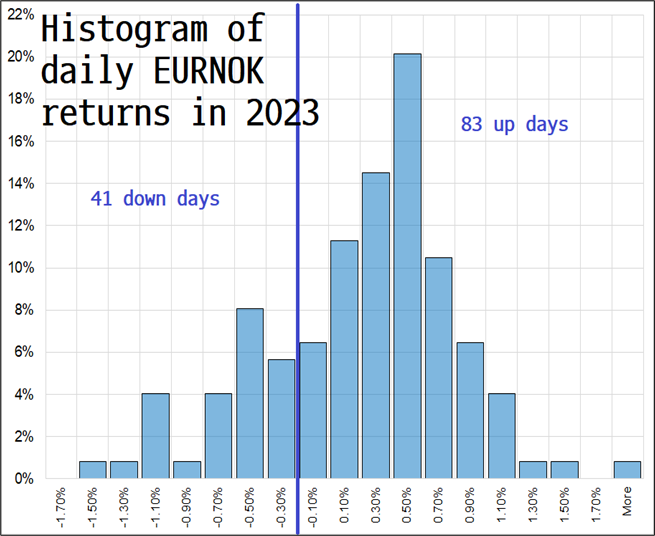
The NASDAQ is up 30% this year, the correlation between EURNOK and equities is negative, and yet EURNOK has gone from 10.45 to 11.86 this year.
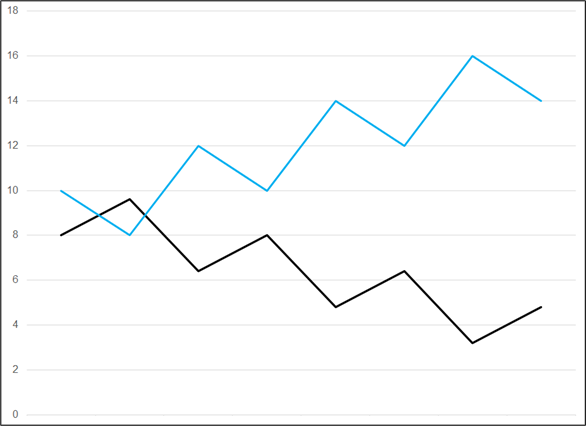
It’s an interesting lesson in the sometimes-counterintuitive way that correlation and direction are not always the same thing because the skew can dominate the direction and magnitude of the path from A to B, even as the ups and downs coincide.
For example, these two series have a 100% positive correlation:
Further on the NOK, recall this chart from my piece in February, am/FX: Why long NOK is not long Norway:
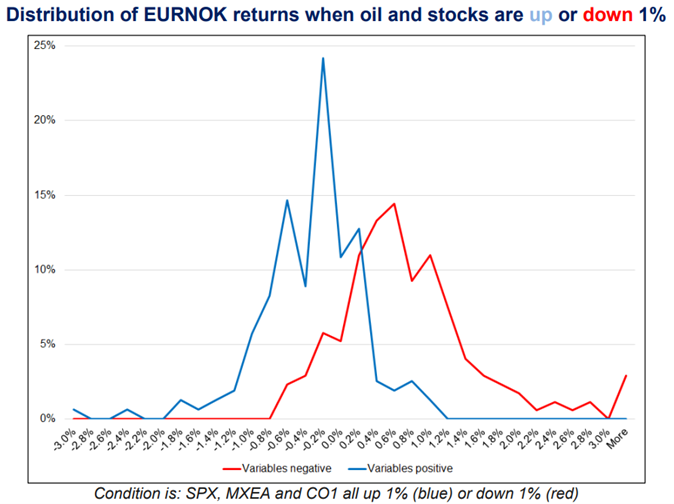
It feels like there is nothing that can save NOK now, other than another one of those huge blowoff tops. Generally, when NOK is in this type of asymmetric regime, it keeps weakening until there is a mega-bid no lid moment and the last of the stubbornest NOK longs is forced to capitulate.
The Ecostanzanomist
If you have been reading my stuff over the past few years, you know that I’m fascinated with how The Economist is a meaningful reverse indicator on a one-year time horizon. Its amazing track record goes back more than two decades. If you are not familiar with why The Economist tends to nail the tops and bottoms of the mainstream narrative (and price), you can read my full article on the phenomenon here.
Yesterday, The Economist put out the cover below and this cover clearly implies that inflation will be sticky. In contrast, a headline like “What if inflation is sticky?” would not meet the criteria for inclusion in the contrarian Magazine Cover Capital portfolio.
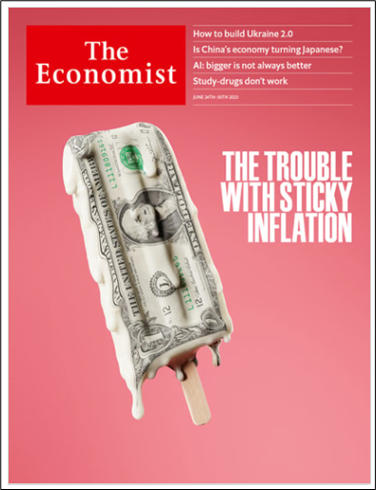
The instrument to express the contrarian view here is probably either long bonds, or short dollars, but the bonds angle seems simplest and clearest to me. Interestingly, there is already both a TLT and an IEF long trade in the portfolio because The Economist has logically been pounding the strong growth and high inflation narrative for a few months.
For this cover, I have chosen long the ZROZ ETF because it is the worst-performing bond ETF over the past three years and thus you can argue it has responded worst to the current bout of high and sticky inflation.
Here are the trades triggered by the Magazine Cover Indicator since my article at the end of 2021. The time horizon on the trades is one year and this is all recorded in real time. There is no hindsight bias or cherry-picking.
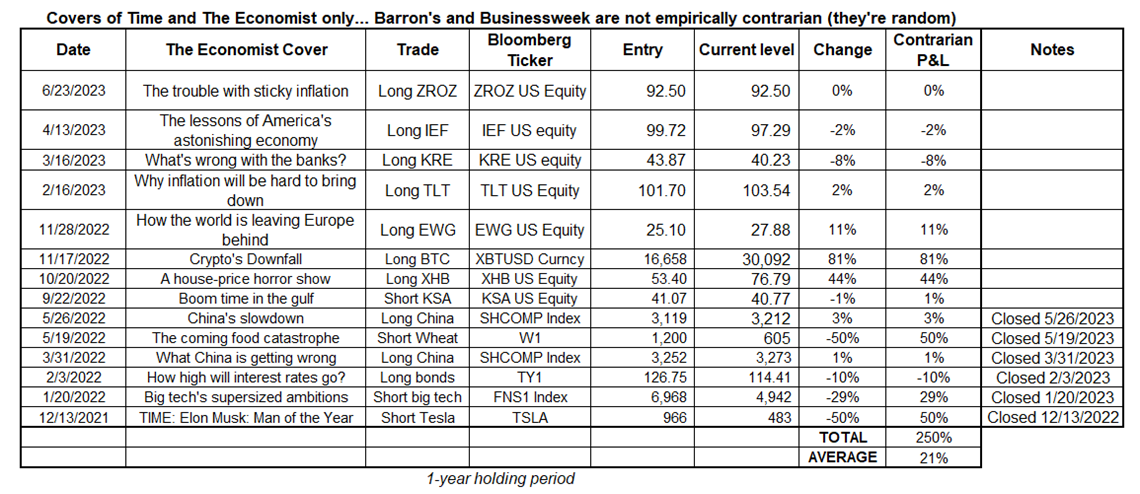
You can see the portfolio is heavily long fixed income, and that the crypto and housing covers from The Economist were incredible, nearly-perfect reverse indicators as both came out within a week of the exact lows in BTC and XHB.
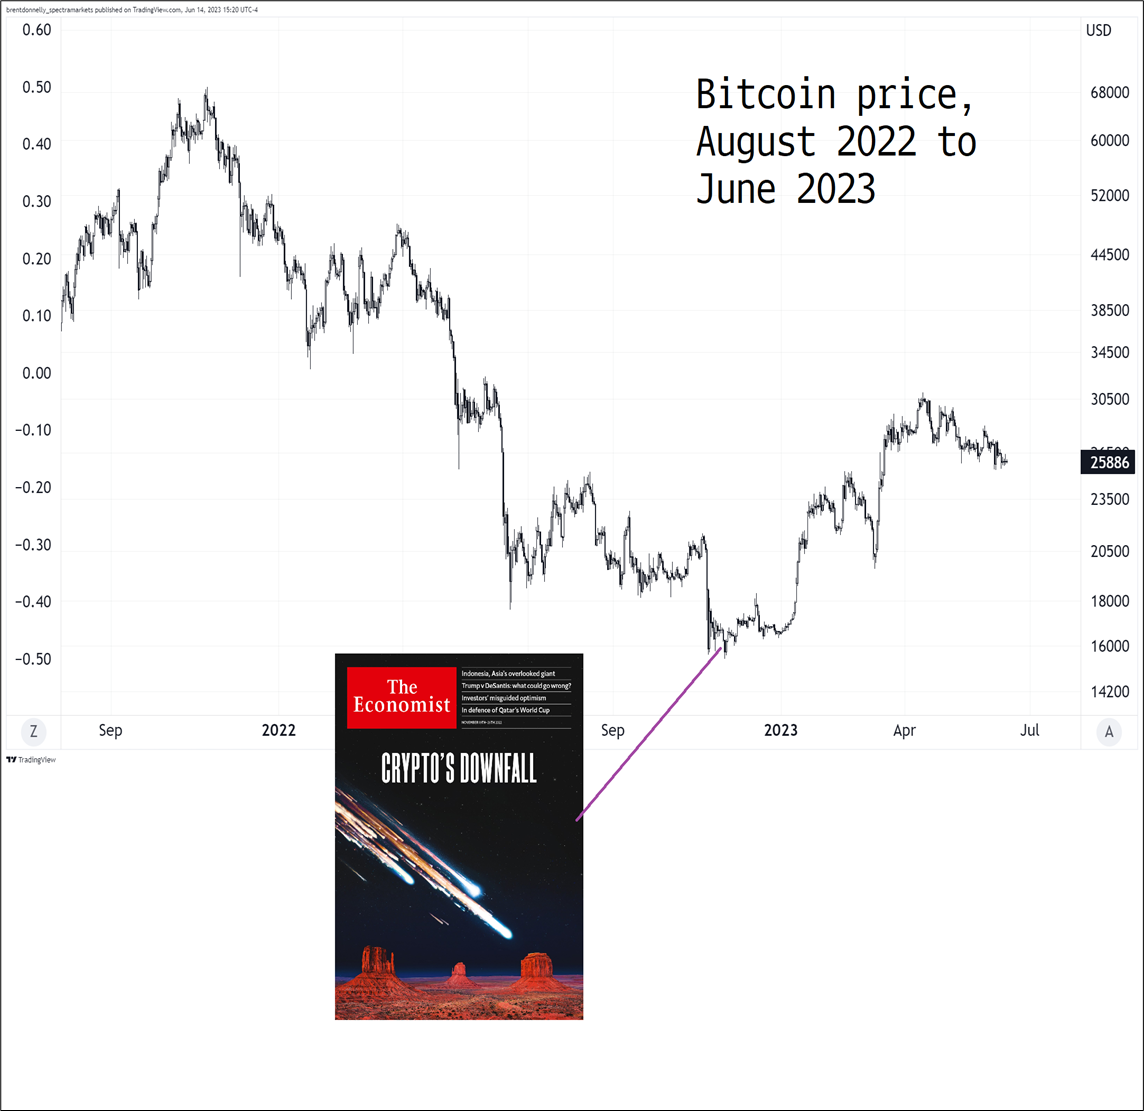
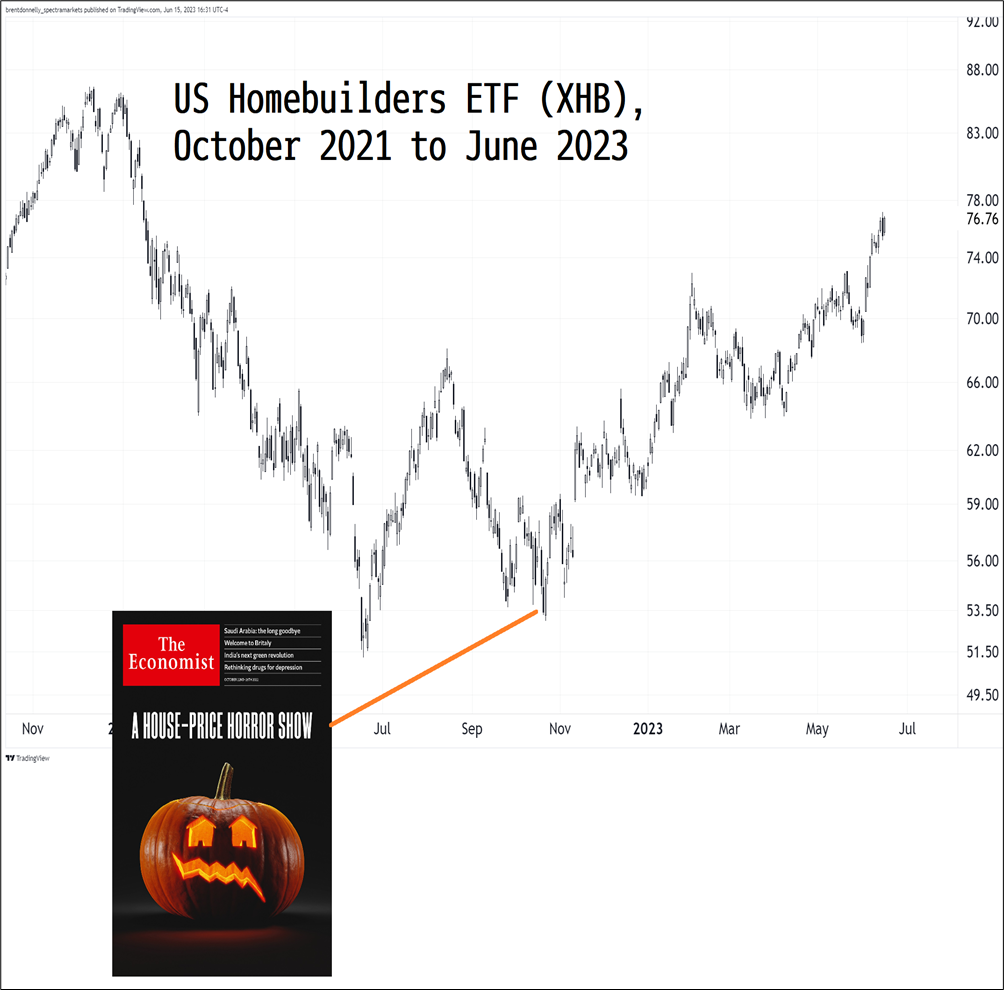
Neat.
The fixed income charts do look mildly interesting as today’s miss in the European PMIs and the move up in bunds is taking US yields lower today. We have been making a triangle of sorts and that triangle looks like it is breaking down. I feel like 10-year yields are kind of like NVDA at 42X sales… I imagine them going much lower, quickly, or a little bit higher, slowly. Here is the 10-year yield chart:
US 10-year yields attempting to break down out of two triangles
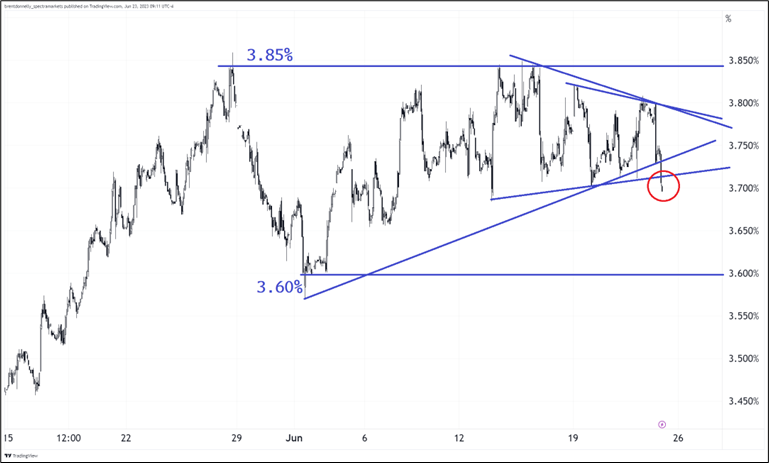
3.60%/3.85% is the range until further notice.
Bitcoin
Bitcoin is alive, kinda. Despite the drop in gold and rise in 2-year yields, the four-factor model described in “am/FX: What is a bitcoin?” still points to higher bitcoin because the NASDAQ has performed so incredibly well since then and that variable dominates.
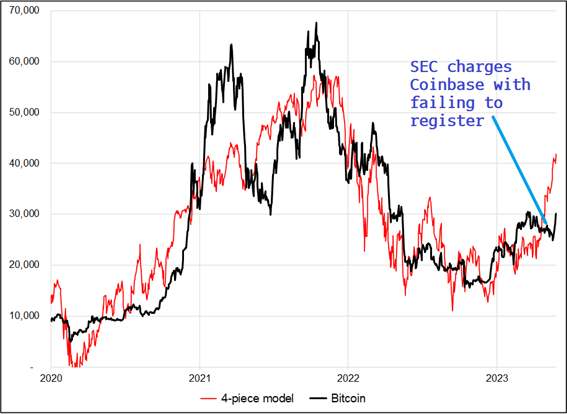
The last push lower in bitcoin after the SEC filed charges against Binance and Coinbase looks to be a fake out as the more cryptocurrencies are named as securities, the stronger the case for bitcoin as the OG store of value. As I have been saying, if NYMEX went bankrupt, that’s not a good reason to sell crude oil.
You can see that the model showed the way in the second half of 2020, called “baloney” on that zippy dip in mid-2021, and turned sharply lower in April 2022 just before bitcoin dumped in May 2022 so it has had some good directional calls.
On the other hand, you could argue that low trading volumes in crypto and the emergence of AI in 2023 mean that a considerable amount of hot money has left the space and is seeking higher volatility elsewhere. NVDA continues to realize higher vol than bitcoin and 0DTE options are more fun that most altcoins, much of the time. As such, I would speculate that some of the gap between the model and BTC is explained by the regime change in interest away from crypto and towards AI and thus will remain persistent. The flurry of spot bitcoin ETF applications has been priced for now and the interminable wait for SEC approval has begun. A decision by Jan/Feb 2024 is likely.
Final thoughts
My CHFJPY idea from last week has been unequivocally bad as carry is still king and the BOJ remains unperturbed, but the drop in European yields gives me the tiniest flicker of hope that I might survive the JPY carnage.
Finally, Key West is cool, and somewhat edgier than I would have suspected. More storefront cannabis stores and drag shows per capita than your average US town! And zillions of help wanted signs everywhere. Have a KKKK kinda day.
good luck ⇅ be nimble