And so do I.
Someone at Target deserves a raise.
And so do I.
Someone at Target deserves a raise.
Short EURUSD and USDJPY 02SEP vol
as described in am/FX on 26AUG (pin trade)
1.1650 vs. 1.16/1.17 and
159.30 vs. 158.80/159.80
Short EURJPY @ 184.80
Stop loss 186.37
09SEP USDCNH call spread
6.7300/6.7400 for 42 CNH pips
10SEP CHFJPY put spread
199/196 for ~37bps off 200.50 spot
30NOV Long 1.23/1.25 AUDNZD c/s vs.
short 1.18/1.19 p/s
~Zero cost off 1.2080
Yesterday, my inbox and chats were flooded with so many AUD bullish pieces that I could not bring myself to think about any bullish AUD ideas. With 24 hours to think about all this, however, I think there is probably a good trade here. The AUD bull theme is well advertised right now and comes down to:
The number of people excited about these trades is a red flag, but this could be the start of a bullish narrative, not the end of one. There is a big difference between a stale theme that is getting a ton of attention, and a newish theme that is not yet fully subscribed. I like the AUDNZD view particularly, because I think the election story is underpriced. If the government returns the RBNZ to a dual mandate, that is unequivocally dovish and bearish for NZD. Yet if you look at the curve, there is pretty much nothing priced in for the election right now.
The easiest way to play this trade is to buy something that expires a few weeks after the election and avoid getting super long vol because the market is already on this theme, a bit, and AUDNZD often range trades for long periods. I am going to put an option structure in the sidebar, because I think it’s super high EV, but I acknowledge it can only be done by hedge funds and banks, not retail.
The simpler alternative (long AUDNZD cash) probably works too, but if I were doing that, I would wait to buy a dip to 1.20 and put my stop below 1.1880. You can see here that the 200-day moving averages are a good reassessment trigger if you’re long. Bullish above, bearish below.
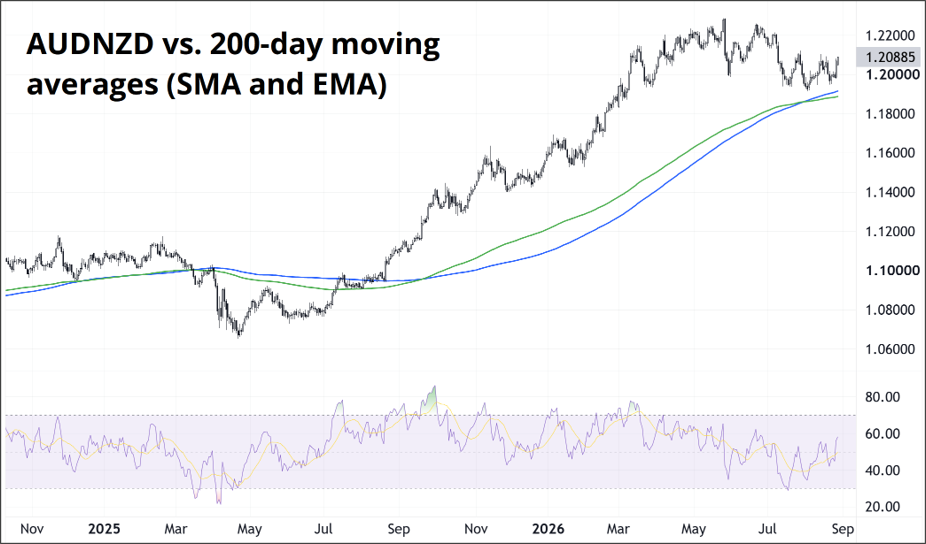
I know this could easily be the 10th bullish AUDNZD rec you have read this week. Sometimes the consensus is correct.
Based on that chart, and my view that the election is too cheaply priced in the options market, here is the trade I like. I want to do 3-month, but the 3-month date is Thanksgiving, so I am doing 30NOV.
30NOV26
Buy AUDNZD 1.2300/1.2500 call spread in X million per leg
Sell AUDNZD 1.1900/1.1800 put spread in X million per leg
It’s essentially zero cost (maybe you receive tiny, depending on where spot is trading). The sizing needs to be appropriate so that if AUDNZD collapses, you lose 100 pips on X million AUDNZD and you are fine with that.
E.g., if you want to risk $500,000 USD on this idea, you would do around 84 million AUDNZD and then 1 big fig (1.19 to 1.18) on 84 mio AUDNZD = ~$500k USD.
A little kicker for the AUD side. There is a well-known seasonal quirk in AUD where BHP dividends are bullish for the currency due to conversion to foreign currencies. While this seasonal has been well known for at least 10 years and you see umpteen bank writeups about it every year, it still works. The flow is larger than the spec trading that precedes it. These sorts of anomalies tend to get arbitraged away over time, but it can sometimes take years and years. Anyway, if you look at the performance of AUD before and after the BHP record date for the dividend, the performance is in the table.
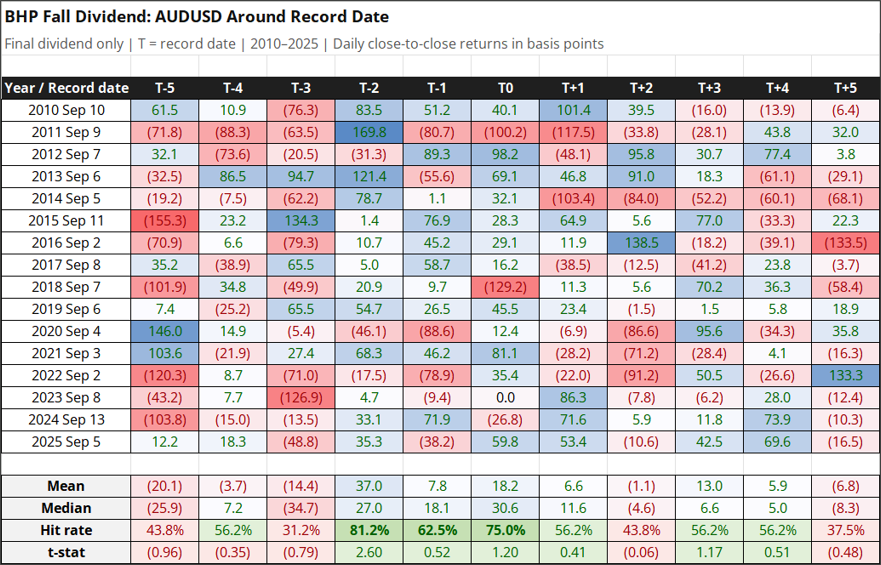
There is false precision in choosing the record date as t=0. BHP can do whatever they want as they utilize different hedging strategies in various years and may have different balance sheet needs for USD vs. AUD etc. What this analysis can do is show you the approximate window around the record date is a worthwhile place to expect some AUD strength. The flow is real. Sure, it’s common knowledge, but it’s also huge. This year’s record date is Friday, September 4, so the window to be long AUD for this effect is approximately 31AUG to 07SEP. This allows for the fact that the market might go a bit early given the popularity of this signal, or BHP might hedge later than usual for random reasons we can’t possibly know. I would not try to be overly precise with the timing on this stuff.
Again, this pattern is about as common knowledge as things get. But it has been common knowledge for years and it keeps working out of sample. EMH on trial.
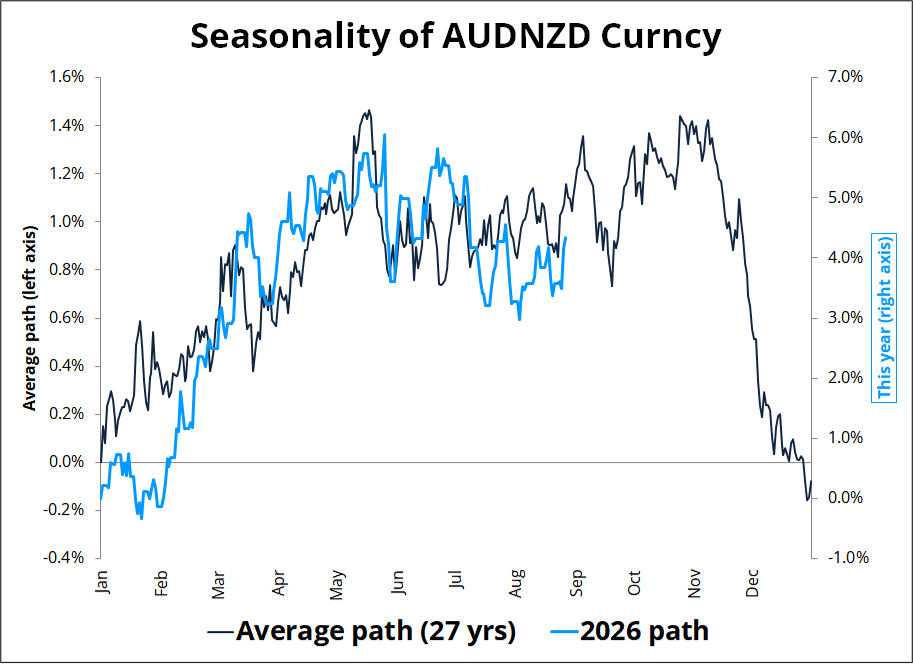
Finally, here’s AUDNZD this year vs. its normal seasonal pattern. Something to watch for if this trade idea starts to work. NZD tends to trade extremely well at the end of the year as USD weakness dominates and NZD is a high-beta USD play.
Finally finally, on the AUDCAD trade, which is as popular right now as the AUDNZD: I hate that. Canada tariffs are irrelevant to the currency in my mind, and AUDCAD is just a short USD proxy. If you’re bearish USD, sure. Otherwise, going long AUDCAD right at massive 1.00 resistance looks like a bad bet to me.
The short software meme that peaked in virality around the daily Claude releases and Citrini’s awesome sci-fi essay has gone into reverse and last night’s flurry of excellent earnings has put the theme to bed for now.
To be clear, I am not being sarcastic about Citrini—the piece was excellent and he was the first to say it was a description of tail risks, not a base case. But the market was rabid at the time and they took IGV down to $74. Now it’s $106 or so and usage of SaaSpocalypse is more retrospectively sarcastic than earnest these days.
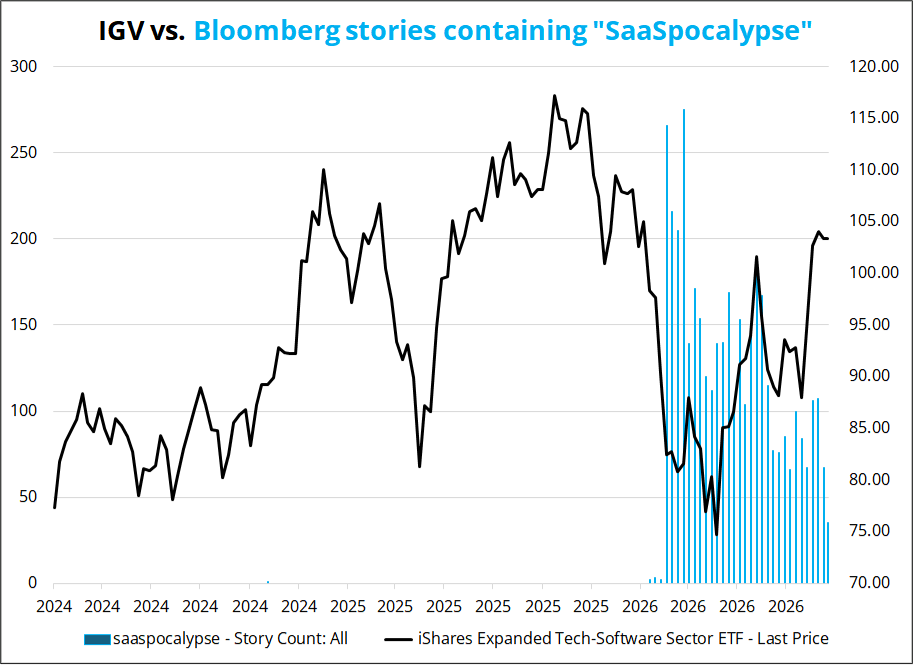
As a funny aside, I was recently doing a similar chart for “TINA” where TINA is “There is no alternative”. That was another funny turn of phrase the market used for American assets when Europe and China were deemed to be uninvestable. I plotted the chart vs. DXY and got this chart.
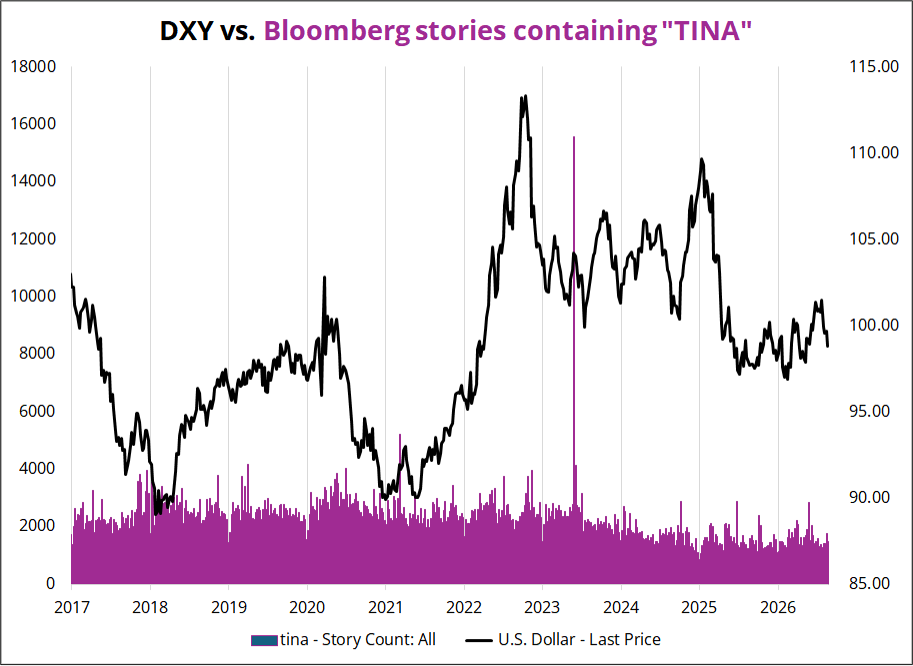
As I pondered what U.S. policy action happened in May 2023, and came up empty—I realized:
That’s when Tina Turner died.
RIP, private dancer.

Have a powerful, cold-blooded, razor-toothed day.